cci
Commodity Channel Index
CCI = (HLC3 - SMA(HLC3)) / (0.015 * MeanDev(HLC3)). Bullish: CCI crosses above -threshold (leaving oversold). Bearish: CCI crosses below +threshold (leaving overbought).
Signal family
Mean reversion — Oscillator-based signals that fire at overbought or oversold extremes — typically fade the prevailing move.
Parameters
| Name | Description | Default | Range |
|---|---|---|---|
| period | CCI period | 20 | 5–100 |
| threshold | Threshold | 100 | 50–200 |
Historical context
4,031,287 triggers on 24,246 tickers, 1988-04-08 → 2026-05-01. Universe: global — all covered exchanges (mcap ≥ $100,000,000, price ≥ $1). Long-only convention: BUY at open T+1, hold the horizon, compare to S&P 500 Equal Weight over the same window.
Methodology footnotes
Benchmarks shown in the detail tables: spxew (S&P 500 Equal Weight — primary, median-stock view, avoids the 2020+ megacap-concentration distortion), spx (S&P 500 cap-weighted, distorted post-2020), msci (MSCI World USD). Per-stock regime tags: trending = ADX(14) ≥ 25, high vol = 20d realized annualized vol ≥ 20%. 1d return = intraday T+1 open→close; 20d = open T+1 to close T+20.
At a glance — alpha vs S&P 500 Equal Weight, global universe
Holding-period sensitivity. Bullish columns: positive = signal worked (long the trigger beat the index). Bearish columns: negative = signal worked (the flagged stock underperformed).
| Horizon | Bullish α | Bearish α |
|---|---|---|
| 5-day | -0.11% | +0.03% |
| 20-day | -0.16% | +0.15% |
| 60-day | +0.07% | +0.47% |
| 1-year | +1.43% | +2.83% |
Bearish: worse than random (p=1.000).
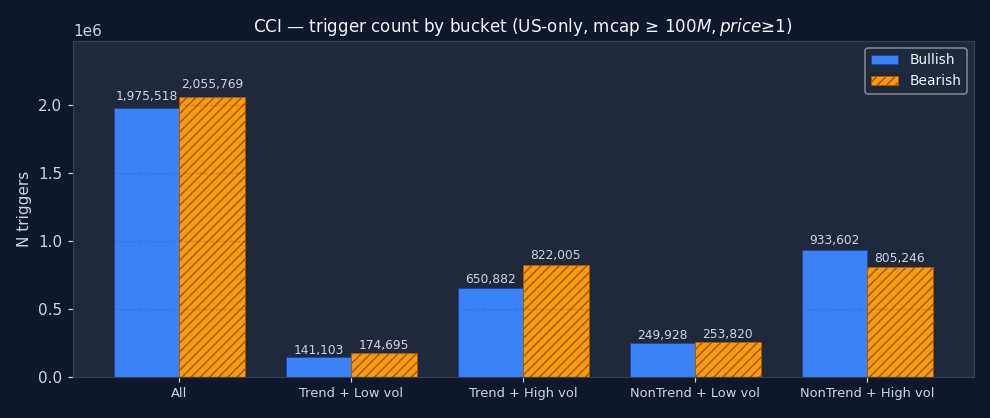
Where does CCI actually fire?
The bucket distribution often reveals what the signal really is, regardless of its textbook label. Heavy concentration in "non-trending + high vol" = it's mostly a chop-market event. Heavy in "trending + low vol" = it picks up the smooth grinds. Read the chart before the alpha numbers — context shapes everything that follows.
Does it work in every regime?
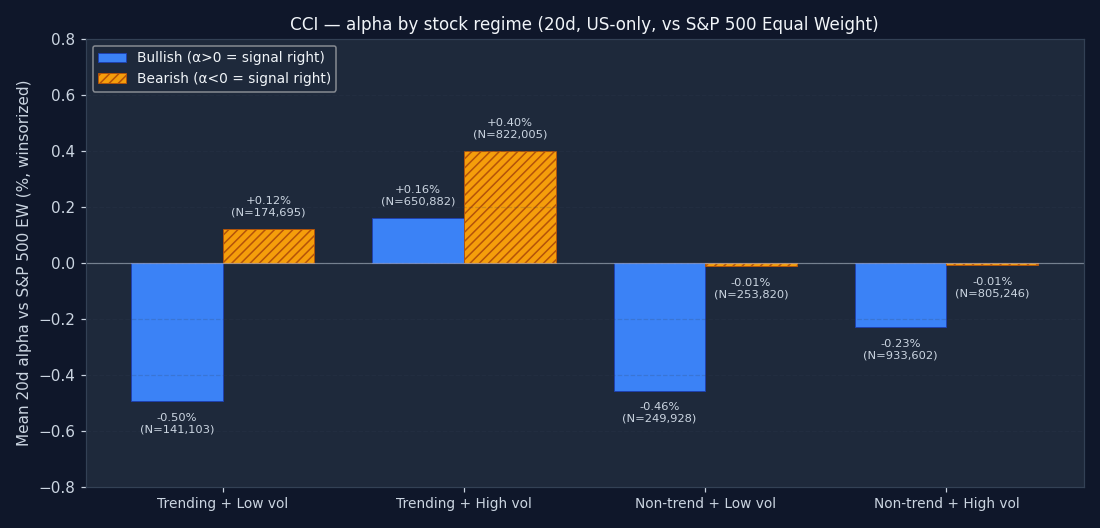
Trigger alpha split by the host stock's own regime on the trigger date — trending or ranging, high-vol or low-vol. This is the 20-day alpha a trade taken on the trigger would have captured. Bars carrying the sign that favours the trade (positive for bullish triggers, negative for bearish) mark the regimes where the signal worked; the opposite sign marks regimes to avoid. One strong bar beside three flat ones is not a "20-day alpha" signal — it is a "20-day alpha when the stock is X" signal. Bar labels carry the sample size; a cell built on a handful of triggers is noise, not a regime finding.
Does it work in every era?
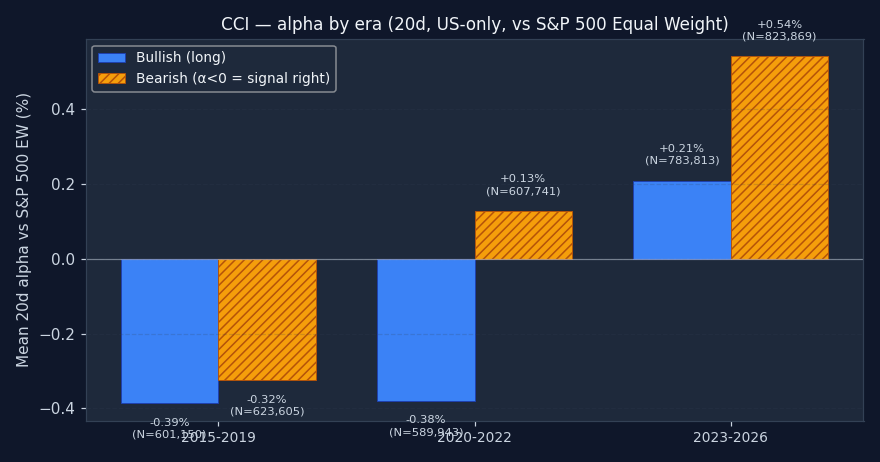
A multi-year average can hide major instability. The sample splits into three windows: 2015–2019 (pre-COVID), 2020–2022 (pandemic + 2022 bear), and 2023+ (post-ZIRP + AI megacap rally). All three carrying the sign that favours the trade means the signal is durable; one era doing all the work means a regime-specific edge that may not repeat. The greater the variance across eras, the smaller the position it justifies.
↑ Bullish triggers
| Bench | Metric | 1d | 5d | 20d | 60d | 252d |
|---|---|---|---|---|---|---|
| spxew | Stock % | +0.01% | +0.16% | +0.99% | +2.92% | +11.91% |
| Bench % | +0.06% | +0.26% | +1.17% | +2.81% | +10.29% | |
| Alpha % | -0.06% | -0.11% | -0.16% | +0.07% | +1.43% | |
| Median alpha | -0.12% | -0.32% | -0.97% | -2.04% | -6.90% | |
| Hit rate (α>0) | 47.0% | 46.5% | 45.1% | 44.2% | 41.4% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | 0.0055 | <0.001 | |
| N | 1,907,198 | 1,837,656 | 1,824,776 | 1,777,851 | 1,604,449 | |
| spx | Stock % | +0.01% | +0.16% | +0.99% | +2.92% | +11.91% |
| Bench % | +0.03% | +0.27% | +1.36% | +3.35% | +14.12% | |
| Alpha % | -0.04% | -0.13% | -0.34% | -0.45% | -2.27% | |
| Median alpha | -0.09% | -0.36% | -1.20% | -2.64% | -10.76% | |
| Hit rate (α>0) | 47.4% | 46.1% | 43.9% | 42.7% | 37.4% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| N | 1,918,030 | 1,852,353 | 1,853,132 | 1,797,529 | 1,629,945 | |
| msci | Stock % | +0.01% | +0.16% | +0.99% | +2.92% | +11.91% |
| Bench % | +0.07% | +0.30% | +1.20% | +2.97% | +11.74% | |
| Alpha % | -0.07% | -0.15% | -0.21% | -0.06% | -0.20% | |
| Median alpha | -0.14% | -0.39% | -1.08% | -2.28% | -8.55% | |
| Hit rate (α>0) | 46.4% | 45.8% | 44.5% | 43.6% | 39.7% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | 0.0151 | 0.1564 | |
| N | 1,905,920 | 1,837,883 | 1,825,413 | 1,782,977 | 1,606,960 |
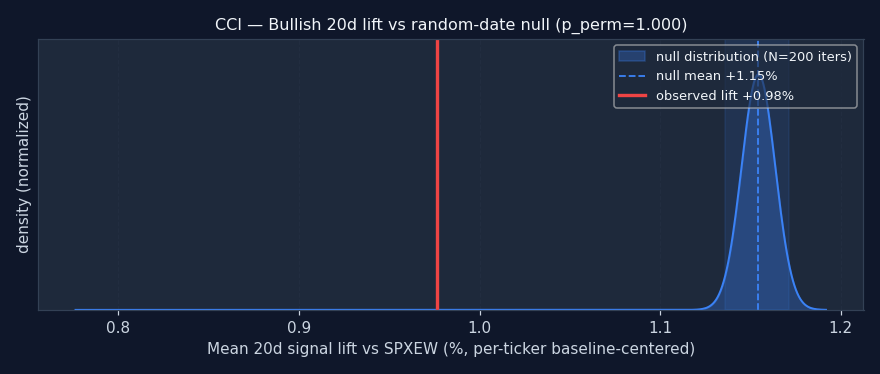
Permutation null detail — all horizons × each benchmark
| Horizon | Bench | Observed lift | Null mean | Null 95% CI | pperm |
|---|---|---|---|---|---|
| 1d | spxew | +0.08% | +0.08% | [+0.08%, +0.08%] | 0.910 |
| 1d | spx | +0.09% | +0.09% | [+0.08%, +0.09%] | 0.910 |
| 1d | msci | +0.08% | +0.09% | [+0.09%, +0.10%] | 1.000 |
| 5d | spxew | +0.28% | +0.36% | [+0.35%, +0.37%] | 1.000 |
| 5d | spx | +0.31% | +0.37% | [+0.36%, +0.38%] | 1.000 |
| 5d | msci | +0.29% | +0.38% | [+0.37%, +0.39%] | 1.000 |
| 20d | spxew | +0.98% | +1.15% | [+1.14%, +1.17%] | 1.000 |
| 20d | spx | +1.02% | +1.18% | [+1.17%, +1.20%] | 1.000 |
| 20d | msci | +1.04% | +1.20% | [+1.18%, +1.21%] | 1.000 |
| 60d | spxew | +2.41% | +2.47% | [+2.44%, +2.50%] | 1.000 |
| 60d | spx | +2.63% | +2.53% | [+2.50%, +2.56%] | 0.005 |
| 60d | msci | +2.61% | +2.55% | [+2.52%, +2.58%] | 0.005 |
| 252d | spxew | +4.96% | +4.79% | [+4.72%, +4.84%] | 0.005 |
| 252d | spx | +5.30% | +5.13% | [+5.06%, +5.18%] | 0.005 |
| 252d | msci | +5.13% | +5.08% | [+5.01%, +5.13%] | 0.040 |
Example triggers on US large-caps (2023+, mcap ≥ $30B)
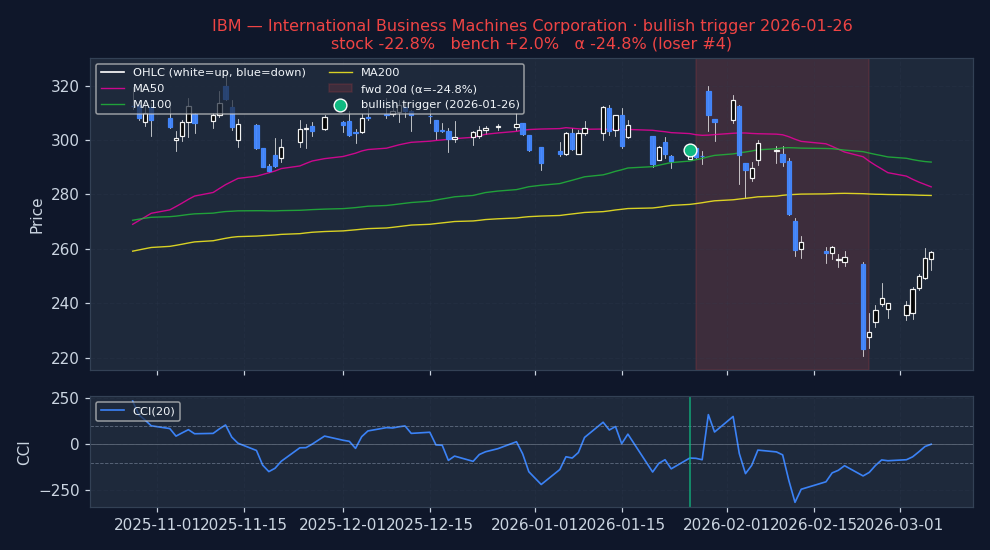
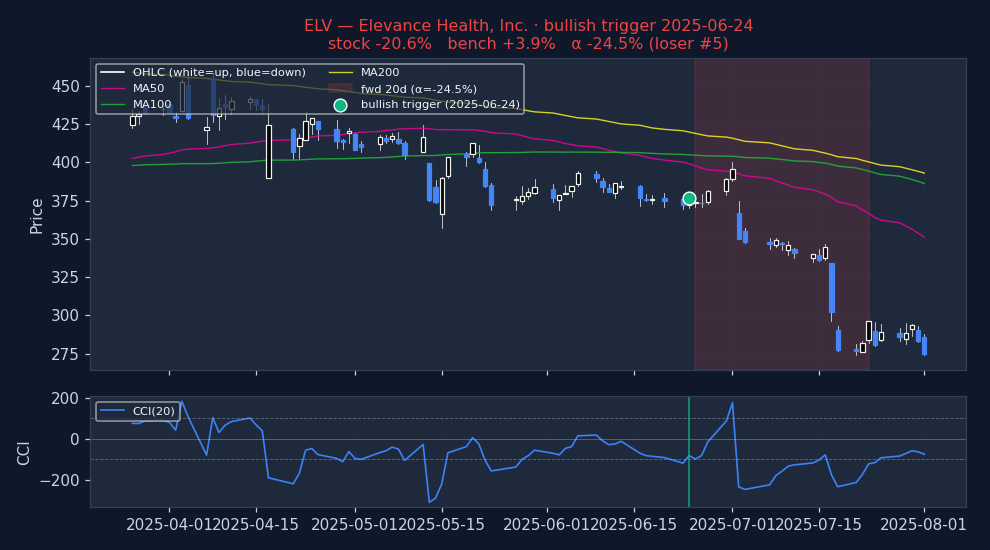
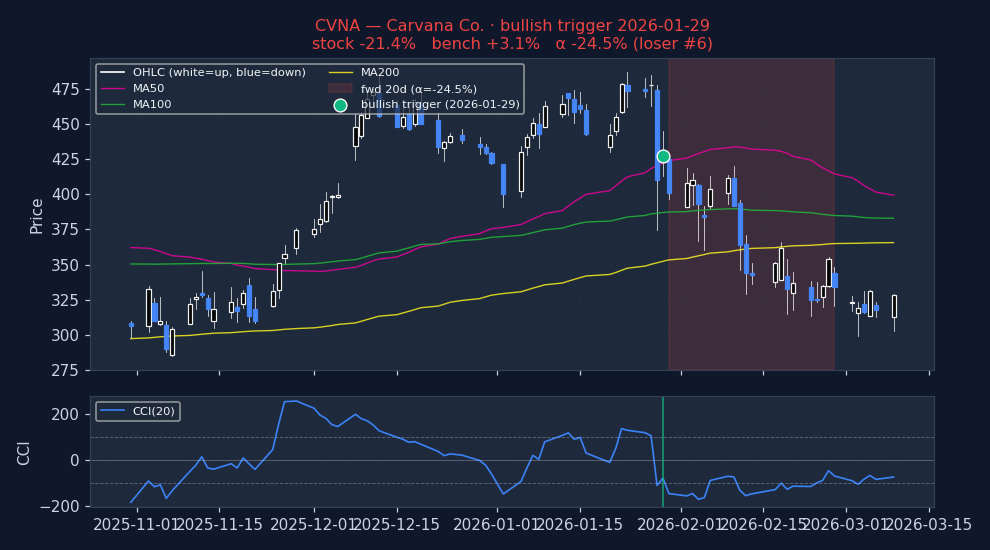
Six recent bullish CCI triggers on US mega-caps, ranked within this sample of six: the top three and the bottom three, with extreme outliers excluded. Ranking is relative, not absolute — where the signal did well across the sampled names, even the bottom three can have beaten the benchmark, so the alpha printed on each panel is what settles it. Both groups are tail outcomes by construction; read them as the range, not the typical result.
Best three of the six sampled
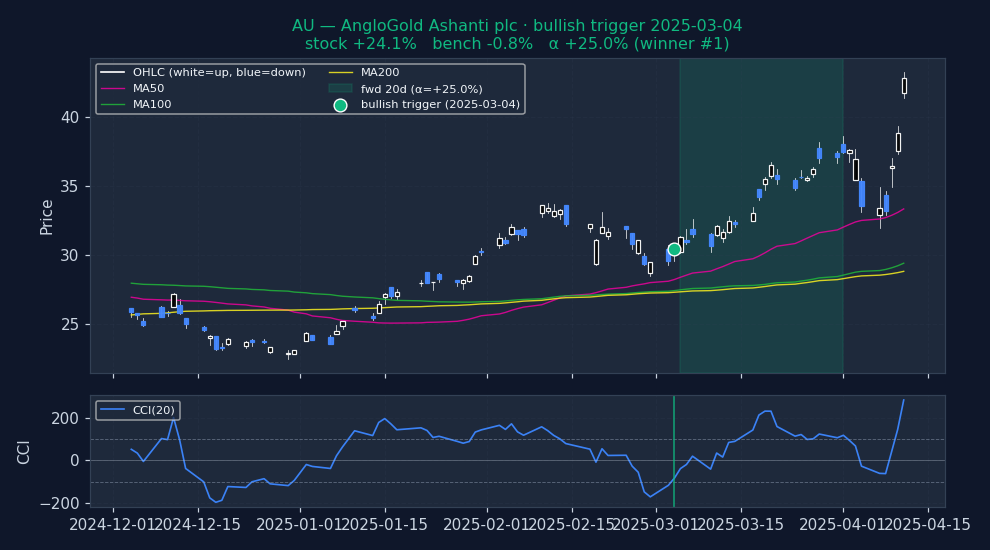
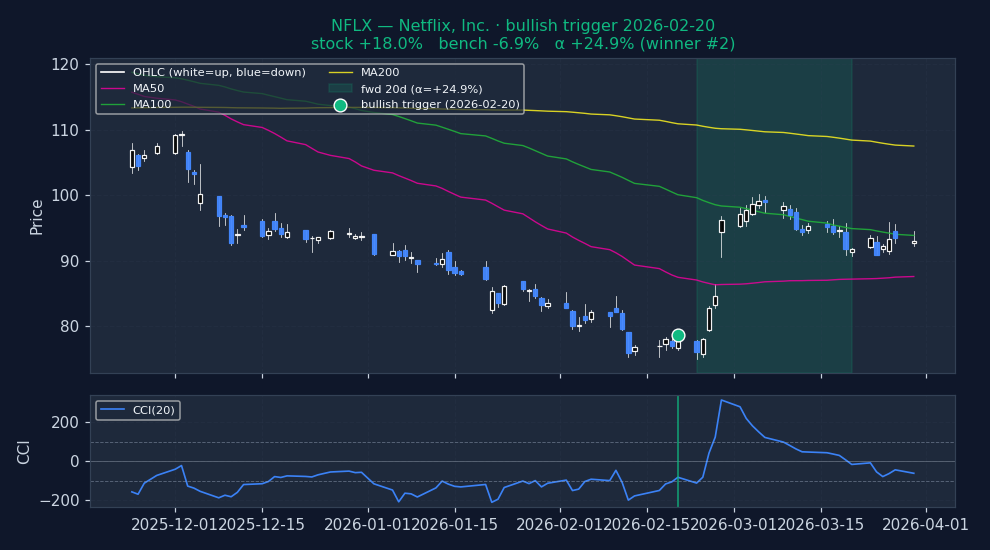
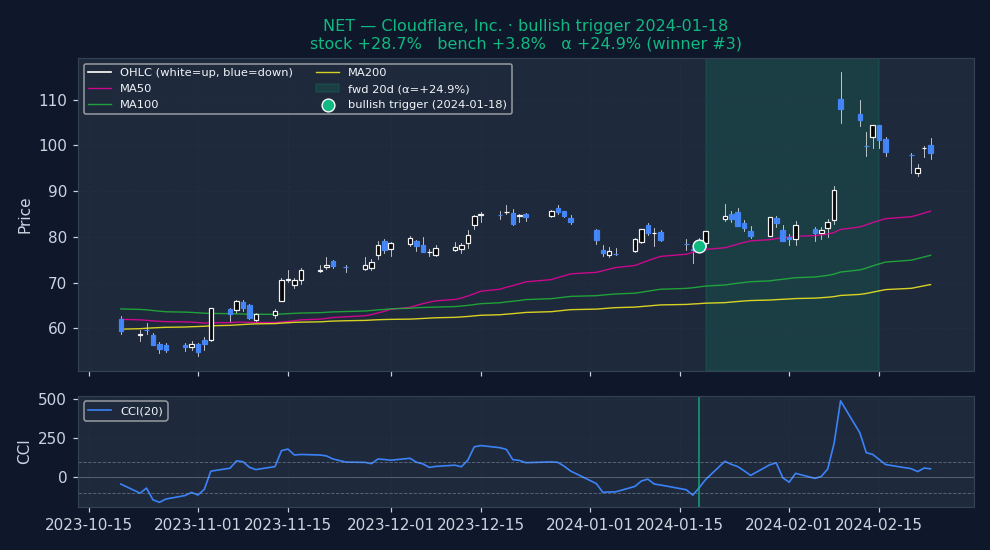
Weakest three of the six sampled — not necessarily losses
Stock-regime quadrants (2×2 per-stock, 20d alpha detail table)
| Quadrant | N | Stock % (spxew) | Bench % (spxew) | Alpha % (spxew) | p (HAC) | Stock % (spx) | Bench % (spx) | Alpha % (spx) | p (HAC) | Stock % (msci) | Bench % (msci) | Alpha % (msci) | p (HAC) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Trending + Low vol Clean directional grind, low whipsaw | 141,103 | +0.29% | +0.85% | -0.50% | <0.001 | +0.29% | +1.08% | -0.75% | <0.001 | +0.29% | +0.93% | -0.60% | <0.001 |
| Trending + High vol Crisis selloff or parabolic rally | 650,882 | +1.54% | +1.33% | +0.16% | <0.001 | +1.54% | +1.56% | -0.02% | 0.2102 | +1.54% | +1.34% | +0.14% | <0.001 |
| Non-trending + Low vol Quiet chop, summer doldrums | 249,928 | +0.31% | +0.80% | -0.46% | <0.001 | +0.31% | +1.04% | -0.71% | <0.001 | +0.31% | +0.92% | -0.58% | <0.001 |
| Non-trending + High vol Classical "whipsaw zone" for momentum | 933,602 | +0.93% | +1.16% | -0.23% | <0.001 | +0.93% | +1.35% | -0.39% | <0.001 | +0.93% | +1.20% | -0.29% | <0.001 |
Sub-period breakdown table (20d alpha)
| Period | N | Alpha % (spxew) | p (HAC) | Alpha % (spx) | p (HAC) | Alpha % (msci) | p (HAC) |
|---|---|---|---|---|---|---|---|
| 2015-2019 2015-01-01 → 2020-01-01 | 601,150 | -0.39% | <0.001 | -0.47% | <0.001 | -0.27% | <0.001 |
| 2020-2022 2020-01-01 → 2023-01-01 | 589,943 | -0.38% | <0.001 | -0.08% | <0.001 | +0.03% | 0.0917 |
| 2023-2026 2023-01-01 → 2099-01-01 | 783,813 | +0.21% | <0.001 | -0.44% | <0.001 | -0.35% | <0.001 |
↓ Bearish triggers negative alpha = signal was right (stock underperformed market)
| Bench | Metric | 1d | 5d | 20d | 60d | 252d |
|---|---|---|---|---|---|---|
| spxew | Stock % | +0.01% | +0.23% | +0.83% | +2.69% | +12.75% |
| Bench % | +0.04% | +0.21% | +0.74% | +2.28% | +10.03% | |
| Alpha % | -0.04% | +0.03% | +0.15% | +0.47% | +2.83% | |
| Median alpha | -0.08% | -0.25% | -0.76% | -1.75% | -5.74% | |
| Hit rate (α>0) | 47.9% | 47.3% | 46.1% | 45.0% | 42.7% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| N | 1,968,940 | 1,895,319 | 1,887,942 | 1,843,619 | 1,625,651 | |
| spx | Stock % | +0.01% | +0.23% | +0.83% | +2.69% | +12.75% |
| Bench % | +0.02% | +0.22% | +0.93% | +3.06% | +13.79% | |
| Alpha % | -0.01% | +0.02% | -0.05% | -0.35% | -1.08% | |
| Median alpha | -0.07% | -0.27% | -1.00% | -2.61% | -9.77% | |
| Hit rate (α>0) | 48.2% | 47.0% | 44.9% | 42.7% | 38.2% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| N | 1,991,110 | 1,926,333 | 1,906,751 | 1,868,433 | 1,646,663 | |
| msci | Stock % | +0.01% | +0.23% | +0.83% | +2.69% | +12.75% |
| Bench % | +0.04% | +0.21% | +0.82% | +2.65% | +11.36% | |
| Alpha % | -0.03% | +0.04% | +0.06% | +0.09% | +1.29% | |
| Median alpha | -0.09% | -0.26% | -0.90% | -2.19% | -7.38% | |
| Hit rate (α>0) | 47.7% | 47.2% | 45.4% | 43.8% | 40.9% | |
| p (naive) | <0.001 | <0.001 | <0.001 | <0.001 | <0.001 | |
| p (HAC) | <0.001 | <0.001 | <0.001 | 0.0027 | <0.001 | |
| N | 1,977,514 | 1,913,828 | 1,903,877 | 1,856,953 | 1,640,328 |
Permutation null detail — all horizons × each benchmark
| Horizon | Bench | Observed lift | Null mean | Null 95% CI | pperm |
|---|---|---|---|---|---|
| 1d | spxew | +0.09% | +0.07% | [+0.07%, +0.08%] | 1.000 |
| 1d | spx | +0.10% | +0.08% | [+0.08%, +0.09%] | 1.000 |
| 1d | msci | +0.11% | +0.09% | [+0.08%, +0.09%] | 1.000 |
| 5d | spxew | +0.38% | +0.33% | [+0.32%, +0.33%] | 1.000 |
| 5d | spx | +0.41% | +0.34% | [+0.33%, +0.35%] | 1.000 |
| 5d | msci | +0.42% | +0.35% | [+0.34%, +0.36%] | 1.000 |
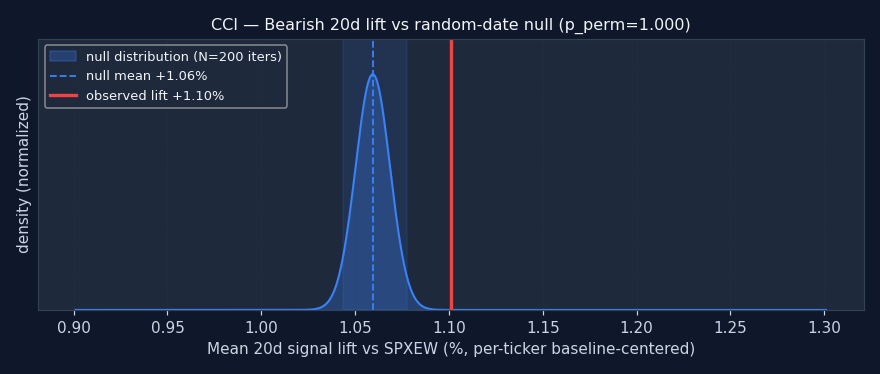
| 20d | spxew | +1.10% | +1.06% | [+1.04%, +1.08%] | 1.000 |
| 20d | spx | +1.13% | +1.09% | [+1.07%, +1.11%] | 1.000 |
| 20d | msci | +1.13% | +1.10% | [+1.09%, +1.12%] | 1.000 |
| 60d | spxew | +2.28% | +2.30% | [+2.27%, +2.33%] | 0.055 |
| 60d | spx | +2.21% | +2.37% | [+2.34%, +2.40%] | 0.005 |
| 60d | msci | +2.23% | +2.39% | [+2.36%, +2.42%] | 0.005 |
| 252d | spxew | +4.44% | +4.46% | [+4.40%, +4.52%] | 0.264 |
| 252d | spx | +4.64% | +4.81% | [+4.76%, +4.87%] | 0.005 |
| 252d | msci | +4.67% | +4.76% | [+4.71%, +4.82%] | 0.005 |
Example triggers on US large-caps (2023+, mcap ≥ $30B)
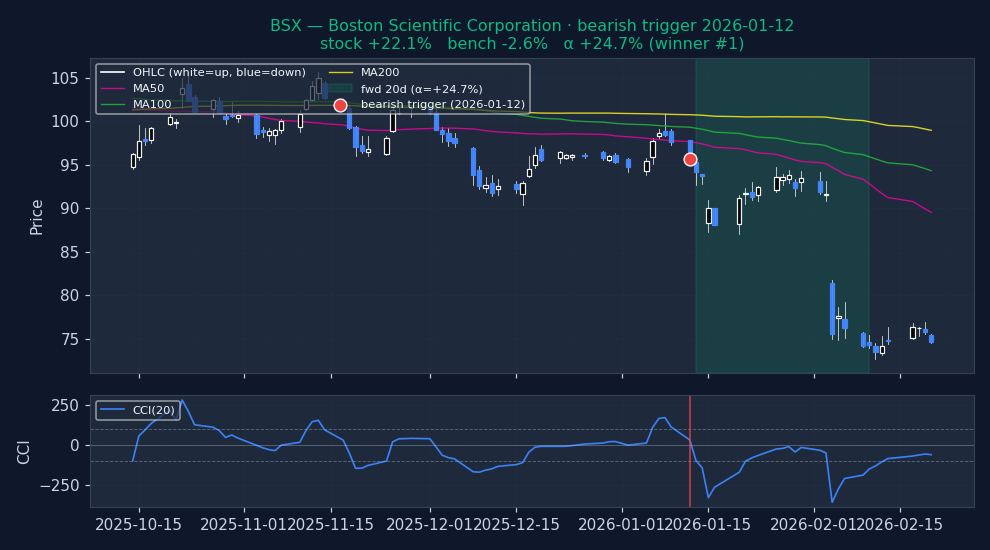
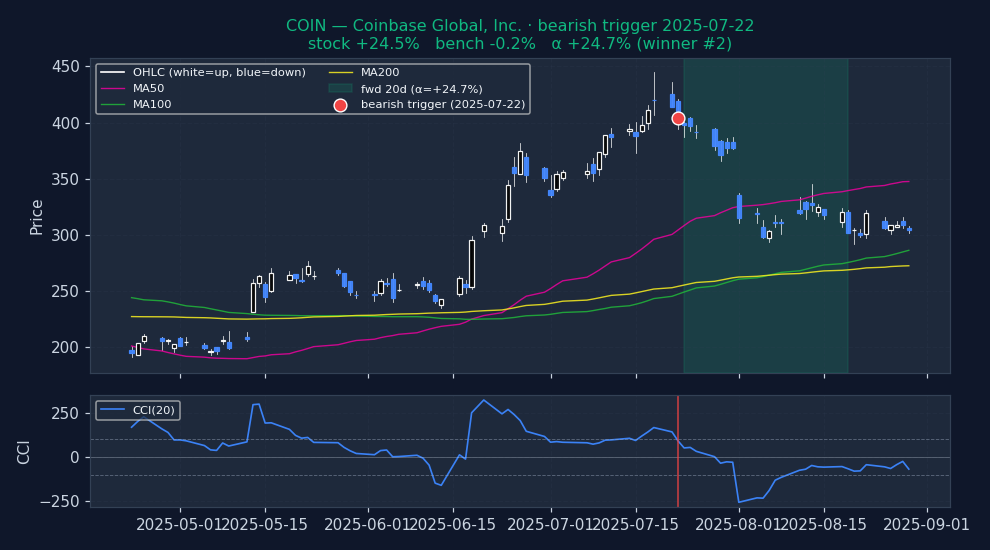
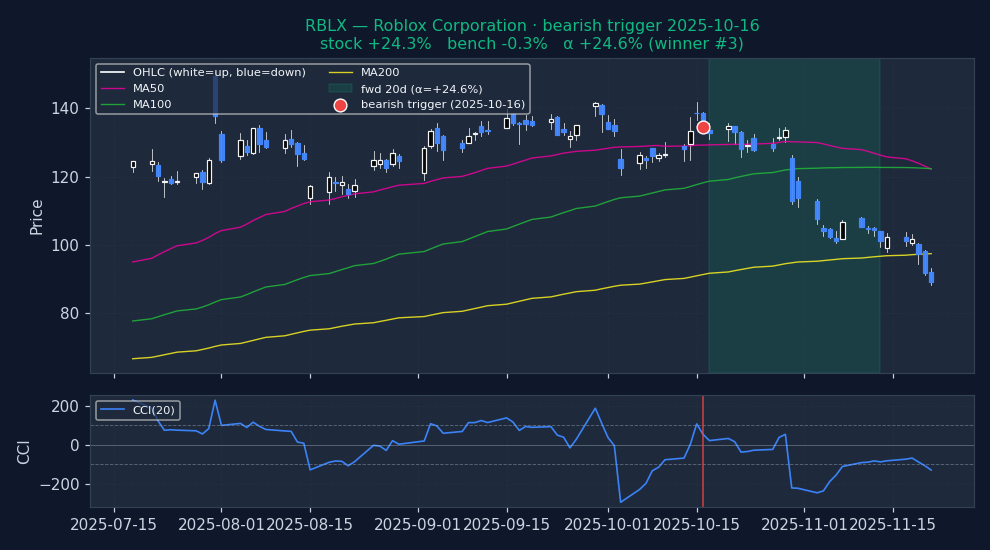
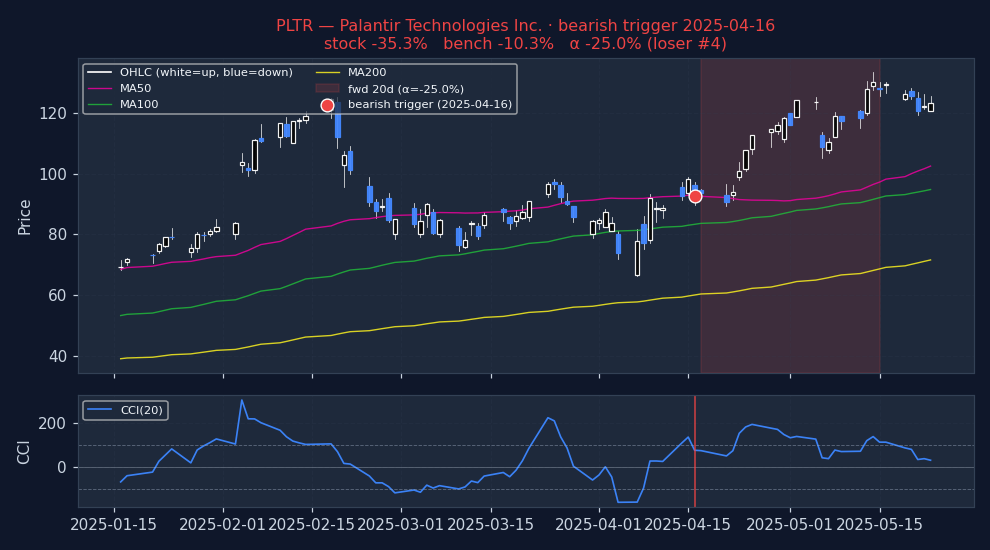
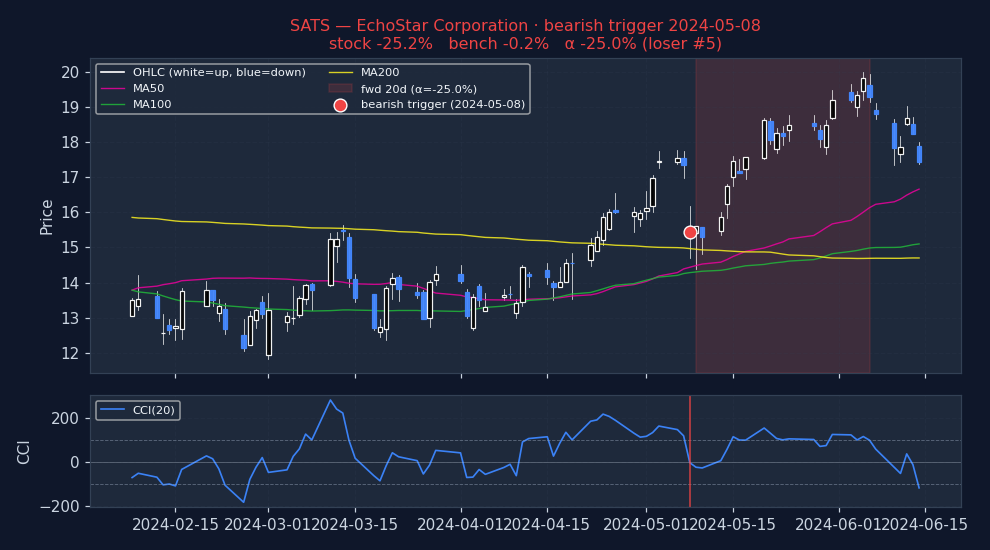
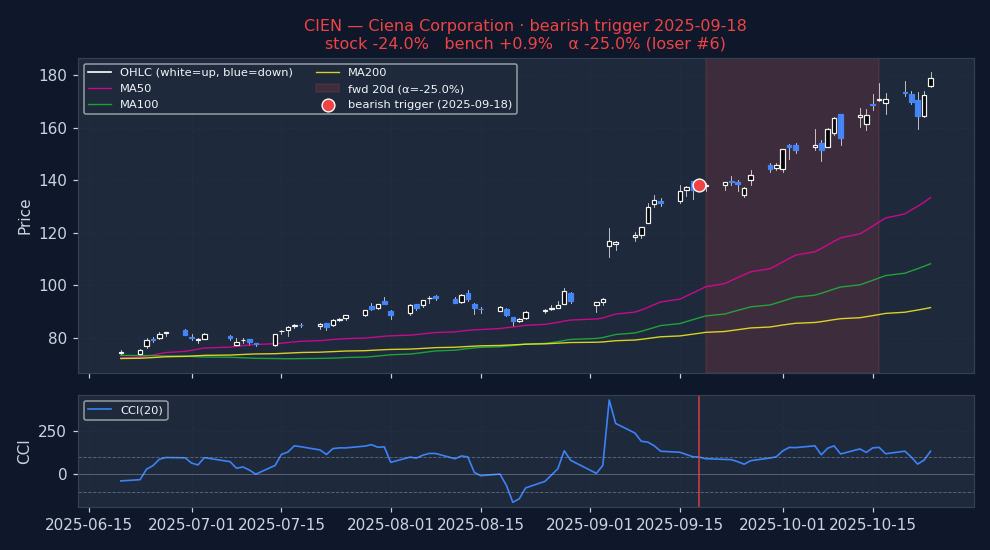
Six recent bearish CCI triggers on US mega-caps, ranked within this sample of six: the top three and the bottom three, with extreme outliers excluded. Ranking is relative, not absolute — where the signal did well across the sampled names, even the bottom three can have beaten the benchmark, so the alpha printed on each panel is what settles it. Both groups are tail outcomes by construction; read them as the range, not the typical result.
Best three of the six sampled
Weakest three of the six sampled — not necessarily losses
Stock-regime quadrants (2×2 per-stock, 20d alpha detail table)
| Quadrant | N | Stock % (spxew) | Bench % (spxew) | Alpha % (spxew) | p (HAC) | Stock % (spx) | Bench % (spx) | Alpha % (spx) | p (HAC) | Stock % (msci) | Bench % (msci) | Alpha % (msci) | p (HAC) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Trending + Low vol Clean directional grind, low whipsaw | 174,695 | +0.50% | +0.41% | +0.12% | <0.001 | +0.50% | +0.72% | -0.20% | <0.001 | +0.50% | +0.57% | -0.05% | 0.0139 |
| Trending + High vol Crisis selloff or parabolic rally | 822,005 | +1.06% | +0.73% | +0.40% | <0.001 | +1.06% | +0.96% | +0.15% | <0.001 | +1.06% | +0.83% | +0.28% | <0.001 |
| Non-trending + Low vol Quiet chop, summer doldrums | 253,820 | +0.48% | +0.53% | -0.01% | 0.4378 | +0.48% | +0.78% | -0.27% | <0.001 | +0.48% | +0.64% | -0.13% | <0.001 |
| Non-trending + High vol Classical "whipsaw zone" for momentum | 805,246 | +0.84% | +0.88% | -0.01% | 0.5512 | +0.84% | +0.99% | -0.12% | <0.001 | +0.84% | +0.92% | -0.04% | 0.0369 |
Sub-period breakdown table (20d alpha)
| Period | N | Alpha % (spxew) | p (HAC) | Alpha % (spx) | p (HAC) | Alpha % (msci) | p (HAC) |
|---|---|---|---|---|---|---|---|
| 2015-2019 2015-01-01 → 2020-01-01 | 623,605 | -0.32% | <0.001 | -0.56% | <0.001 | -0.36% | <0.001 |
| 2020-2022 2020-01-01 → 2023-01-01 | 607,741 | +0.13% | <0.001 | +0.38% | <0.001 | +0.48% | <0.001 |
| 2023-2026 2023-01-01 → 2099-01-01 | 823,869 | +0.54% | <0.001 | +0.03% | 0.1666 | +0.09% | <0.001 |
Methodology and caveats
How to read. Entry at open of T+1 (one trading day after the signal fires on close of T). 20d = open T+1 to close T+20. Alpha = stock return − benchmark return over the same window (Convention A, single-sided, textbook). For bullish triggers, POSITIVE alpha = signal was right. For bearish triggers, NEGATIVE alpha = signal was right (stock underperformed market). No sign-flipping; the direction of the bet determines what "good" looks like. Per-stock regime is each stock's own ADX(14) and RV(20) at the trigger date — not market-wide state.
Three p-values, three robustness tests. (a) p_naive: scipy one-sample t-test on winsorized alphas. Optimistic because overlapping 20d windows on the same ticker inflate effective N. (b) p_hac: Newey-West HAC with lag = horizon — corrects for the overlap and is the academic-finance standard. (c) p_perm: one-sided fraction of 200 random-date null iterations falling in the “signal was right” tail (mean ≥ observed for bullish; mean ≤ observed for bearish). Tests whether the signal beats random date selection at all. A signal that clears all three (pnaive, phac, pperm all < 0.05) has real information; a signal that fails pperm has not beaten random timing whatever the t-test says — and because the test is one-sided, a pperm up at its 1.000 ceiling is not "no edge" but inverted edge: every random draw served the claimed direction better than the trigger dates did.
Caveats. (i) Universe reflects today's active tickers; delisted losers pruned → survivorship bias. (ii) Mcap ≥ $100M filter uses today's snapshot, not point-in-time — mild lookahead on which stocks enter the sample, not on returns. (iii) Means and p-values use winsorized alphas (1/99 percentile) to prevent data errors from dominating. Medians and hit rates use raw data. (iv) Zero transaction costs assumed. Realistic bid-ask + commissions remove 20–40bps from 20d alpha on US large-caps, more on small-cap. Sub-20bps alpha is noise in practice. (v) Past performance does not predict future results.
How to use this
1 · When to reach for this signal
Not a standalone entry trigger at 20 days. Bullish 20d alpha is -0.16% — worse than random : firing on random dates would have done better. Bearish 20d alpha is +0.15% — worse than random : firing on random dates would have done better. Fires are screening context inside a composite (section 4), not entries.
These verdicts are 20-day holds vs S&P 500 Equal Weight. Longer horizons can differ in either direction — check the permutation detail tables below before extrapolating.
2 · When it works — the setups that drive it
- Best bullish setup: Trending + High vol — alpha +0.16% / 20d on 650,882 historical triggers.
- Best bearish setup: Non-trending + Low vol — alpha -0.01% / 20d on 253,820 historical triggers.
- Best era for bullish: 2023-2026 — alpha +0.21% / 20d on 783,813 triggers.
- Best era for bearish: 2015-2019 — alpha -0.32% / 20d on 623,605 triggers.
3 · When it fails — common false positives
- Weakest bullish cell: Trending + Low vol — alpha -0.50% / 20d on 141,103 triggers.
- Weakest bearish cell: Trending + High vol — alpha +0.40% / 20d on 822,005 triggers.
- Worst era for bullish: 2015-2019 — alpha -0.39% / 20d on 601,150 triggers.
- Worst era for bearish: 2023-2026 — alpha +0.54% / 20d on 823,869 triggers.
Signal-specific failure patterns
4 · Pairing inside a screen
The statements below describe how this signal relates to others by construction — which indicator family it belongs to, and where same-family redundancy might reduce the independence of evidence inside a Daily Report. These are taxonomic classifications drawn from standard technical-analysis texts; they are not pairing backtests. Measured pair results — same-day co-fires put through the pair backtest — follow under “Measured pairings” below.
Oscillator-family redundancy
CCI belongs to the momentum-oscillator family alongside RSI, Stochastics, and Williams %R — each is a short-lookback price oscillator read against reference bands (their constructions differ — CCI scales typical price (H+L+C)/3 around its own mean and is unbounded, RSI smooths close-to-close changes into a 0-100 scale, Stochastics and Williams %R place the close inside the recent high-low range — but they respond to the same underlying move) (Murphy, Technical Analysis of the Financial Markets, 1999; Pring, Technical Analysis Explained, 5th ed. 2014; Kirkpatrick & Dahlquist, Technical Analysis, 3rd ed. 2015). Stacking two or more of these in the same direction within a single Daily Report produces correlated rather than independent evidence.
Measured pairings — Bonferroni survivors
Beyond the literature pairings above, these are the same-day co-fire combinations involving Commodity Channel Index that cleared the pair backtest's Bonferroni cut on the full 2016–2026 sample (549 pairs × 5 horizons = 2,745 hypotheses), on universes filtered to ADV ≥ $5M, price ≥ $5 and market cap ≥ $100M. That cut is two-sided: it asks only whether the co-fire's α is reliably different from zero, in either direction, so a pair can survive by reliably underperforming — 3 of the 24 rows below do exactly that (negative full-sample α). The same run holds out 2023+: the Test columns are that held-out window, printed for every row with enough held-out co-fires to measure, so a survivor that did not repeat out of sample is visible rather than hidden. All α figures here are for holding the stock long after the co-fire — no shorting assumed, and no sign flip for bearish legs. So positive α means the co-fire was followed by outperformance and negative α by underperformance, whichever way either leg points — a bearish leg does not flip the reading. Survivors are rare by design — absence of a pair here means it did not clear the cut, not that it was untested. Ranked by held-out (2023+) α. Historical tendencies, not recommendations.
US (NYSE / NASDAQ / AMEX)
| Pair (same-day co-fire, long) | Full α | Test α (2023+) | Test N | p_perm test |
|---|---|---|---|---|
| cci bullish + stochastics bullish | +0.30% | +0.45% | 18,538 | 0.002 |
1 of this universe's 18 surviving pairs involves this signal · α vs ^SPXEW.
Europe — 5 surviving pairs
| Pair (same-day co-fire, long) | Full α | Test α (2023+) | Test N | p_perm test |
|---|---|---|---|---|
| cci bearish + rsi bearish | +0.60% | +0.77% | 3,073 | 0.002 |
| cci bearish + vwap_cross bearish | +0.46% | +0.42% | 3,165 | 0.010 |
| cci bearish + williams_r bearish | +0.33% | +0.35% | 11,506 | 0.002 |
| cci bearish + stochastics bearish | +0.37% | +0.34% | 6,544 | 0.002 |
| cci bullish + williams_r bullish | +0.35% | +0.08% | 9,070 | 0.321 |
5 of this universe's 20 surviving pairs involve this signal · α vs ^STOXX.
Hong Kong — 1 surviving pair
| Pair (same-day co-fire, long) | Full α | Test α (2023+) | Test N | p_perm test |
|---|---|---|---|---|
| cci bearish + williams_r bearish | +0.58% | +0.86% | 3,398 | 0.002 |
1 of this universe's 23 surviving pairs involves this signal · α vs ^HSI.
China A-shares — 17 surviving pairs
| Pair (same-day co-fire, long) | Full α | Test α (2023+) | Test N | p_perm test |
|---|---|---|---|---|
| cci bearish + hh_hl_streak bearish | +2.53% | +4.75% | 4,169 | 0.002 |
| cci bullish + weekly_change bearish | +2.67% | +3.62% | 1,244 | 0.002 |
| cci bullish + rsi bullish | +2.33% | +3.00% | 7,856 | 0.002 |
| cci bearish + ma_crossover bullish | +1.65% | +2.10% | 743 | 0.002 |
| cci bearish + new_20d_low bearish | +0.96% | +1.47% | 881 | 0.002 |
| bollinger bullish + cci bullish | +1.24% | +1.38% | 4,902 | 0.002 |
| cci bullish + macd bullish | +0.74% | +1.01% | 9,273 | 0.002 |
| cci bearish + rsi bearish | +0.88% | +0.92% | 8,915 | 0.002 |
| cci bullish + hh_hl_streak bullish | +2.01% | +0.68% | 1,787 | 0.040 |
| cci bullish + williams_r bullish | +0.48% | +0.67% | 55,921 | 0.002 |
| cci bearish + williams_r bearish | +0.35% | +0.62% | 40,420 | 0.002 |
| cci bullish + stochastics bullish | +0.35% | +0.56% | 35,021 | 0.002 |
| cci bearish + stochastics bearish | +0.22% | +0.47% | 25,460 | 0.002 |
| cci bullish + vwap_cross bullish | +0.32% | +0.38% | 13,463 | 0.002 |
| cci bearish + volume_breakout bearish | -0.90% | -0.26% | 5,895 | 0.140 |
| cci bearish + volume_breakout bullish | -2.10% | -0.58% | 330 | 0.475 |
| cci bullish + williams_r bearish | -4.02% | — | — | — |
17 of this universe's 138 surviving pairs involve this signal · α vs 83188.HK.
China A-share survivor α runs large but skews toward small-caps, where trading costs and thin liquidity claim a large share of any measured edge — screening context, not a capturable spread.
“—” in the test columns means the held-out 2023+ sample fell below the 20-observation minimum this run requires before it computes any statistic, so no out-of-sample figure exists for that pair — not that it never co-fired again. Those pairs rank last.
What would likely rescue this signal
This block calls out the data or conditions that could turn a technically weak signal into a usable one in a composite screen. Based on signal mechanics and the observed failure patterns above; individual combinations are not yet backtested.
- Regime-gate bullish on breadth — Bullish CCI is a bet that beaten-down typical prices revert, which historically depends on how broad market participation is. Gating bullish fires on a breadth threshold, or on the benchmark trading some distance below its high, is a testable refinement — check the sub-period breakdown above for whether the current data motivates it.
- Let the table set the bearish hold — Compare the 20d and 60d columns in the current tables before choosing exits. Alpha that builds with horizon argues for time-stops over profit targets; flat or reversing columns argue for shorter holds. Because CCI fires frequently, per-fire position sizing matters more than for rarer signals — its triggers are many small correlated bets, not a few independent ones.
See also Why technical-only signals don't survive on their own for the broader argument.
5 · Before acting — a 5-point checklist
- Normal trading day? Rule out earnings (within ±3 days), ex-dividend, or known corporate-action dates — the signal is almost certainly reading noise, not momentum, in those windows.
- Where is price vs its own 50 / 200 DMA? A mean-reversion signal firing against the long-term trend (e.g. oversold in a clean uptrend) is much more reliable than one firing with it.
- What's the sector breadth doing? An isolated signal in a broadly down-trending sector is a lower-confidence setup than one firing with the rest of its peer group.
- Is ADV20 enough for the intended size? A $1M notional order in a $500M name moves the tape by itself. A useful floor is adv20d ≥ 5% of the intended position.
- What invalidates the trade? Define a price level in advance (for longs: a close below the trigger-day low; for shorts: a close above the trigger-day high) and honour it. The backtest alpha is an average; any single trade can land at either tail.
Execution notes
Entry convention in the tables above is next-day open (open T+1). CCI here is Lambert's original 1980 construction: (typical price minus its 20-day simple moving average) / (0.015 × mean deviation), with thresholds at ±100. Under the single-sided long convention used in the tables, a bearish fire 'works' when post-trigger alpha is negative — the stock lags the benchmark after firing. Take direction from the current data: a side that clears the random-date permutation null can serve as a screen tile in that direction; a side that does not is context, not a trade prompt. Historical tendency, not a recommendation.