Weekly Market Breadth Report — September 18, 2026
Generated automatically from Chartlas market data; methodology at /docs/methodology. Not investment advice.
Market Overview
S&P 500 was roughly flat this week (-0.1%) to 7,650. MSCI World (ACWI) lost -0.6% to 159. Momentum is mid-range (4/6) while trend structure is weak (1/6). The trend has been broken but momentum has not collapsed — the strongest setup in our backtest: +3.4% average over the following 4 weeks vs +1.1% baseline. Best performer: Nikkei 225 (+1.6%). Weakest: Dow Jones (-1.7%).
| Metric | This Week | Last Week | 1Y Avg | Z (1Y) |
|---|---|---|---|---|
| Bullish Signal % | 53.2% | 41.8% | 52.7% | +0.1 |
| Bullish Signals | 102,081 | 72,965 | ||
| Bearish Signals | 89,639 | 101,671 |
Signal balance is near its 1-year norm — nothing unusual this week.
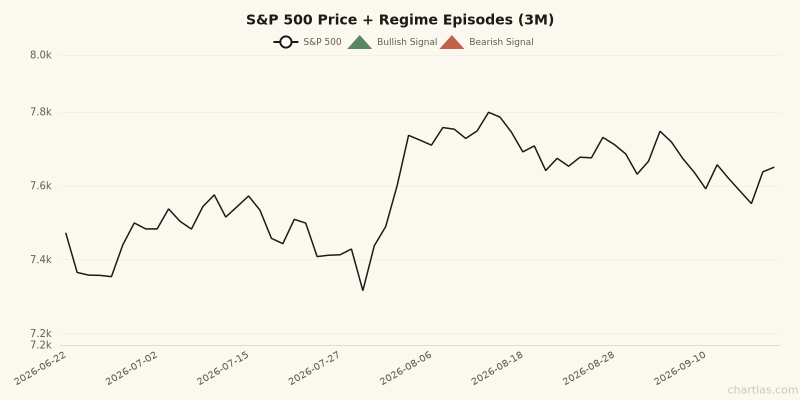
S&P 500 with regime episode markers — one marker per episode, matching the /regime monitor. Green = washouts / 90% up-volume days, red = global Hindenburg episodes / 90% down-volume days.
Key Takeaways
- 🟡 S&P 500: Flat this week at 7,650 (-0.1%).
- 🟡 Breadth: Momentum improving while trend deteriorating — a divergence. Short-term bounce within structural weakness. Modestly above-average forward returns historically, though not statistically significant.
- 🟢 MSCI World fired a bullish stochastic cross on Thursday (chart, Sep 17, index at 4,922) — slow %K turned up through %D from the oversold zone. Since 2015, the five sessions after this cross have averaged +0.7% against +0.2% for a typical five-session stretch, finishing positive 68% of the time (n=103). A modest historical tilt, not a forecast.
- 🔴 The weak side is one theme too — Eastern Europe. 5 of the bottom 8 industry readings are Eastern Europe groups.
- 🟡 Energy tripped the thin-rally flag in 2 regions this week (Middle East & Africa, Latin America; 42 members combined) — prices at or near one-year highs while 10-day breadth runs negative. The same flag, same sector, independently across regions: the rally has outrun its own participation. It resolves by breadth catching up or price coming back.
- 🟡 The regime board is quiet. No washout (50% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Stocks with the Most Signals
Large-cap stocks ($10B+) with 5+ signals fired this week.
| Symbol | Name | Sector | Signals | Net | 1W % |
|---|---|---|---|---|---|
| CRWD | CrowdStrike Holdings, Inc. | Technology | 21 | +15 | +15% |
| ITRK.L | Intertek Group plc | Industrials | 21 | +5 | +0% |
| ULS | UL Solutions Inc. | Industrials | 19 | -15 | -10% |
| RVTY | Revvity, Inc. | Healthcare | 19 | +11 | +15% |
| 601669.SS | Power Construction Corporation | Industrials | 19 | -3 | +0% |
| FRO | Frontline plc | Energy | 16 | +6 | +4% |
| 601127.SS | Seres Group Co.,Ltd | Consumer Cyclical | 16 | +4 | +2% |
| ILMN | Illumina, Inc. | Healthcare | 16 | +10 | +16% |
Regime Monitor
The three breadth conditions that carried a measured forward edge in our backtest, tracked as episodes. Full detail at chartlas.com/regime.
| Marker | State on Sep 18, 2026 | Last episode | Past 12 months |
|---|---|---|---|
| Breadth washout (S&P, <20% above 200-DMA) | 49.8% — neutral zone | Apr 8, 2025 | 0 |
| Hindenburg Omen (global universe) | quiet | Jun 1, 2026 | 3 episodes |
| 90% down-volume day (S&P) | none this week | Dec 31, 2025 | 2 |
| 90% up-volume day (S&P) | none this week | May 27, 2025 | 0 |
How we read it: nothing on the board argues for either aggression or defense right now — the washout gauge sits at 50%, mid-zone. The washout line at 20% is the nearer boundary if the current move extends. 3 global Hindenburg episodes inside twelve months is above the long-run cadence of roughly two — the split-market condition (heavy new highs and new lows together) keeps recurring, and the month after an episode has averaged about three points below a typical month in our history. The most recent (Jun 1, 2026) is stale; a fresh one would move this from footnote to headline. No 90% volume days this week (last down-day episode: Dec 31, 2025).
Where the Signals Are — Industry Scan
The week's cumulative signal net per industry (Investable universe), scored against that industry's own year of weekly readings. Click any name to open it in the Explorer.
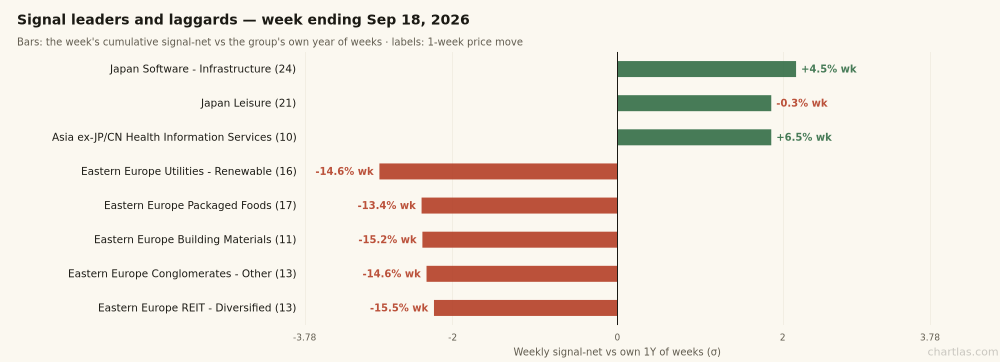
Bars: the week's cumulative signal-net vs the group's own year of weeks. Labels: the same group's 1-week price move.
Signal leaders:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Japan Software - Infrastructure | +96 | +2.2σ | 24 | +4.5% |
| Japan Leisure | +65 | +1.9σ | 21 | -0.3% |
| Asia ex-JP/CN Health Information Services | +39 | +1.9σ | 10 | +6.5% |
Signal laggards:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Eastern Europe Utilities - Renewable | -89 | -2.9σ | 16 | -14.6% |
| Eastern Europe Packaged Foods | -90 | -2.4σ | 17 | -13.4% |
| Eastern Europe Building Materials | -81 | -2.4σ | 11 | -15.2% |
| Eastern Europe Conglomerates - Other | -77 | -2.3σ | 13 | -14.6% |
| Eastern Europe REIT - Diversified | -52 | -2.2σ | 13 | -15.5% |
The read. The strongest surge has trend-family confirmation: Japan Software - Infrastructure logged 120 bullish signals this week, 97 of them trend-type (breakouts, structure, moving-average confirmations) against 23 oversold-type. That is a rally the engine is confirming, not bottom-fishing.
The laggards are equally one theme — Eastern Europe — and there the composition inverts: of Eastern Europe Utilities - Renewable's 132 bearish fires this week, 118 were trend-family breakdowns. Downtrend intact — another week, more groups.
Rotation & Divergences
Structural flags from the CHRT tree this week.
Energy tripped the thin-rally flag in 2 regions this week (Middle East & Africa, Latin America; 42 members combined) — prices at or near one-year highs while 10-day breadth runs negative. The same flag, same sector, independently across regions: the rally has outrun its own participation. It resolves by breadth catching up or price coming back.
Leadership changes worth noting (which industry drives its group's signal activity): - Western Europe Utilities — Western Europe Renewable Utilities took the lead from Western Europe Regulated Utilities (09-14). - Japan Healthcare — Japan Pharma took the lead from Japan Medical Devices (09-14).
Sharpest single-day surprises: Western Europe Telecom printed a -91 net signal day on 09-18 (-4.9σ); Western Europe Telecom Services printed a -90 net signal day on 09-18 (-4.9σ) — worth a look if you own the space.
Geography Scan
The week's cumulative signal net per region vs that region's own year of weekly readings, alongside the week's price move.
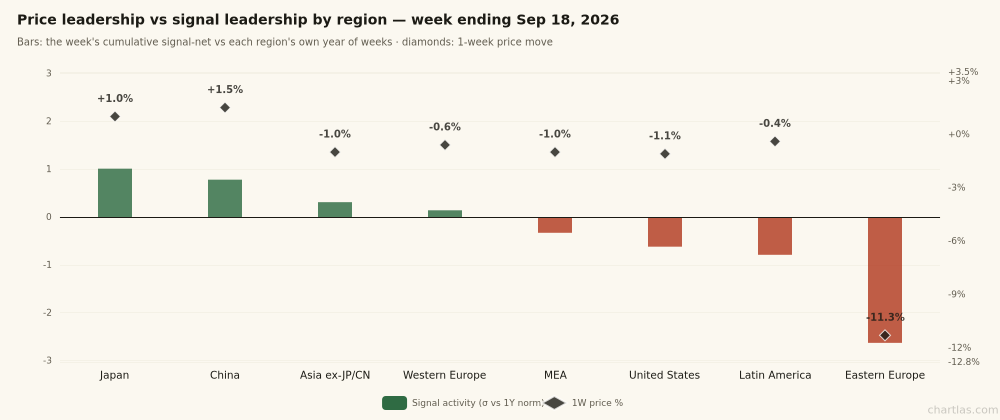
Bars: the week's cumulative signal-net vs each region's own year of weeks. Diamonds: 1-week price move.
| Region | Weekly net | σ (1Y wks) | 1W price |
|---|---|---|---|
| Japan | +4,130 | +1.0σ | +1.0% |
| China | +8,210 | +0.8σ | +1.5% |
| Asia ex-JP/CN | +2,787 | +0.3σ | -1.0% |
| Western Europe | +923 | +0.1σ | -0.6% |
| Middle East & Africa | -108 | -0.3σ | -1.0% |
| United States | -1,045 | -0.6σ | -1.1% |
| Latin America | -322 | -0.8σ | -0.4% |
| Eastern Europe | -1,523 | -2.6σ | -11.3% |
The read: Japan: signal accumulation (+1.0σ) ahead of a flat tape (+1.0%) — participation building before price. Eastern Europe is red on both counts: -11.3% with a -2.6σ signal week.
Momentum Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Advance / Decline | +341 | -24,656 | +24,997 | +0.2 | Flipped bullish |
| New 20D High/Low | -11,290 | -9,308 | -1,982 | -1.5 | Weakening |
| MACD Breadth | +11 | -2,875 | +2,886 | +0.0 | Flipped bullish |
| RSI Extremes | +857 | -766 | +1,623 | +1.0 | Flipped bullish |
| Bollinger Band | +4,188 | -229 | +4,417 | +2.0 | Flipped bullish |
| Weekly Movers (±10%) | -2,330 | +1,478 | -3,808 | -0.9 | Flipped bearish |
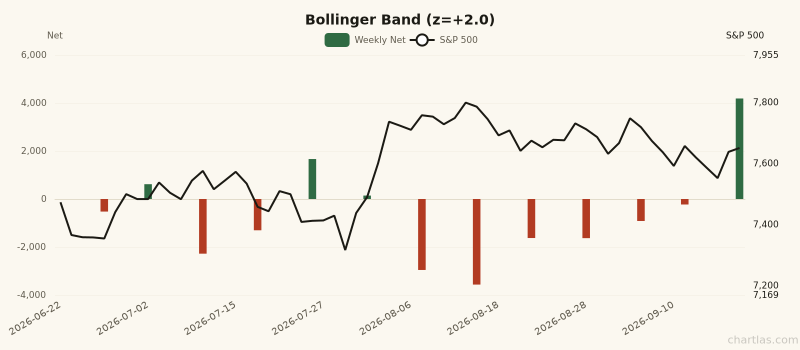
Bollinger Band weekly net (bars) with S&P 500 price (right axis). 1Y z-score: +2.0.
Trend Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| 52-Week High/Low | -2,404 | -1,092 | -1,312 | -1.4 | Weakening |
| Fresh 52W High/Low | -380 | -305 | -75 | -1.3 | Weakening |
| 200 DMA Breadth | -23,482 | -17,172 | -6,310 | -1.6 | Weakening |
| MA Cross (Golden/Death) | -123 | -1 | -122 | -0.3 | Weakening |
| HH/HL Structure | +261 | +104 | +157 | +0.2 | Strengthening |
| Breakout / Breakdown | -60 | +403 | -463 | -1.4 | Flipped bearish |
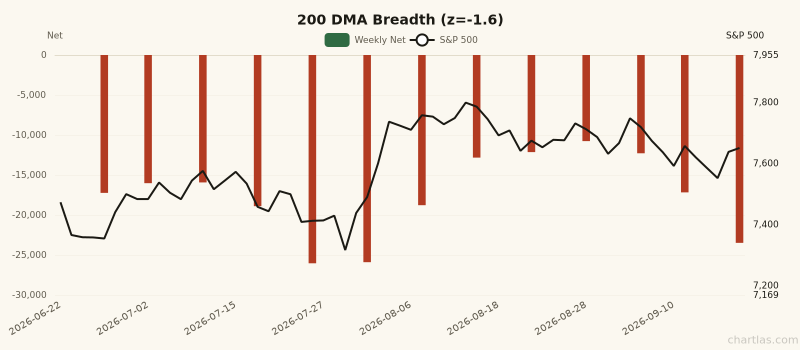
200 DMA Breadth weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -1.6.
Pattern Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Double Top/Bottom | -317 | -181 | -136 | -0.9 | Weakening |
| Failed Pattern | -95 | -142 | +47 | -0.4 | Improving |
Major ETF Signals
| Ticker | Name | Momentum | Trend | Pattern | Net | Z (1Y) |
|---|---|---|---|---|---|---|
| EFA | EAFE (Dev ex-US) | 5↑ 2↓ | — | — | +3 | +0.4 |
| IBIT | Bitcoin | 3↑ | 1↑ 1↓ | — | +3 | +0.6 |
| QQQ | NASDAQ 100 | 3↑ 1↓ | 1↑ | — | +3 | +0.2 |
| SPY | S&P 500 | 5↑ 2↓ | — | — | +3 | +0.1 |
| GLD | Gold | 3↑ 1↓ | — | — | +2 | +0.0 |
| TLT | 20+ Year Treasury | 3↑ | 1↓ | — | +2 | +0.7 |
| USO | Oil (USO) | 3↑ 3↓ | 2↑ | — | +2 | +0.2 |
| DIA | Dow Jones | 4↑ 2↓ | 2↓ | — | +0 | -0.3 |
| EEM | Emerging Markets | 3↑ 2↓ | 1↓ | — | +0 | -0.4 |
| VGK | FTSE Europe | — | — | — | +0 | — |
| IWM | Russell 2000 | 3↑ 2↓ | 2↓ | — | -1 | -0.7 |
| HYG | High Yield Corp | 5↑ 3↓ | 4↓ | — | -2 | -0.7 |
| EWJ | Japan | 3↓ | — | — | -3 | -1.2 |
ETF board quiet again — 4 weeks running inside 2σ.
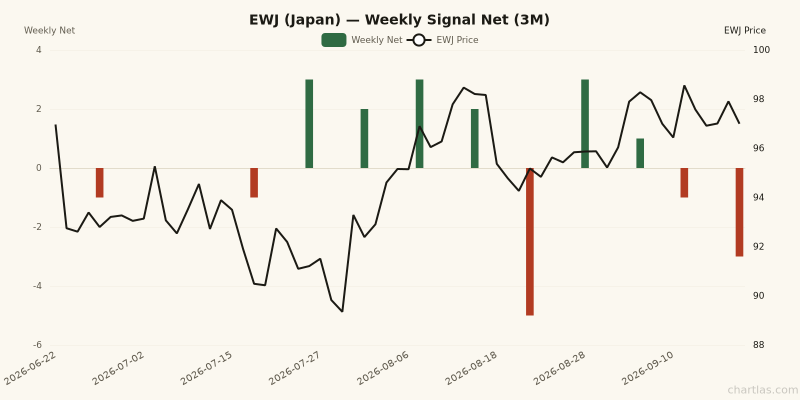
EWJ weekly net signals (bars) with EWJ price (blue line, right axis). 1Y z-score: -1.2.
Sector Breadth (Advance/Decline)
| Sector | Net | % Bullish | Z (1Y) |
|---|---|---|---|
| Technology | +1,743 | 55.2% | +0.9 |
| Industrials | +1,168 | 52.6% | +0.6 |
| Healthcare | +667 | 53.1% | +0.8 |
| Basic Materials | -172 | 49.3% | +0.0 |
| Communication Services | -213 | 47.4% | -0.1 |
| Consumer Cyclical | -285 | 49.0% | +0.1 |
| Utilities | -300 | 44.7% | -1.2 |
| Energy | -342 | 44.4% | -1.1 |
| Real Estate | -472 | 46.0% | -0.5 |
| Consumer Defensive | -525 | 46.2% | -0.4 |
| Financial Services | -892 | 46.0% | -0.8 |
No sector's advance/decline week stands out against its own year — rotation, not conviction.
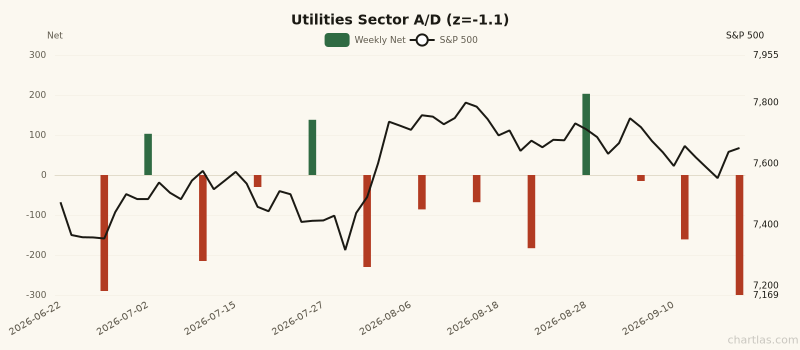
Utilities sector weekly A/D net with S&P 500 price (right axis). 1Y z-score: -1.1.
What to Watch Next Week
- Does trend confirm? Momentum flipped (Advance / Decline); the rally graduates from bounce to trend only if 200 DMA Breadth or 52-Week High/Low turns positive.
- The thin-rally flags. Either breadth catches up (flags resolve quietly) or the first red week hits these groups hardest.
- MACD Breadth at +11 — nearest to a sign flip. Watch which side it picks.
- The confirmed rallies (Japan groups, +4% to +4% price weeks): whether trend-family confirmation persists, or the moves digest.
Last Week We Said
From our report of Sep 11, 2026:
- 🟡 S&P 500: Flat this week at 7,657 (-0.8%).
- 🔴 MSCI World (ACWI): Lost -1.0% — selling pressure is global.
- 🔴 The weak side is one theme too — United States. 3 of the bottom 8 industry readings are United States groups.
Last week's report leaned cautious (0 green, 4 amber, 2 red). What happened: the S&P moved -0.1%. Mixed week, mixed call — no point claimed either way. The tally continues next week.
Generated by Chartlas — equity screening & signal alerts for discretionary investors. Forward-return references are averages from our 2015–2026 backtest on ~31,000 securities; they are tendencies, not predictions. Full methodology on the Regime and Breadth pages. Not investment advice.
Get this report in your inbox every Saturday
Free for all Chartlas users. Plus daily signal alerts, custom screens, PDF exports, and live breadth/regime dashboards.
Create free account →