Weekly Market Breadth Report — October 02, 2026
Generated automatically from Chartlas market data; methodology at /docs/methodology. Not investment advice.
Market Overview
S&P 500 was roughly flat this week (-0.3%) to 7,723. MSCI World (ACWI) lost -0.6% to 160. Both momentum (2/6) and trend (0/6) are weak. Broad weakness across timeframes — slightly above-average forward returns from mean-reversion. Best performer: Nikkei 225 (+2.9%). Weakest: CAC 40 (-2.2%).
| Metric | This Week | Last Week | 1Y Avg | Z (1Y) |
|---|---|---|---|---|
| Bullish Signal % | 44.9% | 51.1% | 52.3% | -0.9 |
| Bullish Signals | 79,049 | 82,008 | ||
| Bearish Signals | 97,034 | 78,394 |
Slightly more bearish than the 1-year weekly average (z=-0.9).
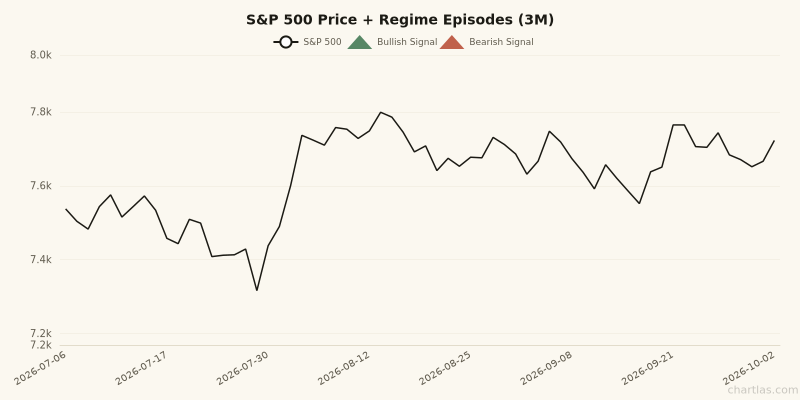
S&P 500 with regime episode markers — one marker per episode, matching the /regime monitor. Green = washouts / 90% up-volume days, red = global Hindenburg episodes / 90% down-volume days.
Key Takeaways
- 🟡 S&P 500: Flat this week at 7,723 (-0.3%).
- 🔴 Breadth: Both momentum (2/6) and trend (0/6) are weak. Broad weakness across timeframes — slightly above-average forward returns from mean-reversion.
- 🔴 The weak side is one theme too — Asia ex-JP/CN. 3 of the bottom 8 industry readings are Asia ex-JP/CN groups.
- 🟡 The regime board is quiet. No washout (42% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Stocks with the Most Signals
Large-cap stocks ($10B+) with 5+ signals fired this week.
| Symbol | Name | Sector | Signals | Net | 1W % |
|---|---|---|---|---|---|
| 6594.T | Nidec Corporation | Industrials | 19 | -9 | -26% |
| J36.SI | Jardine Matheson Holdings Limi | Industrials | 18 | +2 | -1% |
| OTP.BD | OTP Bank Nyrt. | Financial Services | 17 | -13 | -12% |
| BIOC.CA | GLAXO SMITH KLINE | — | 17 | +7 | +37% |
| 0175.HK | Geely Automobile Holdings Limi | Consumer Cyclical | 16 | -6 | -6% |
| FICO | Fair Isaac Corporation | Technology | 16 | -8 | -23% |
| UTHR | United Therapeutics Corporatio | Healthcare | 16 | +10 | +14% |
| LISN.SW | Chocoladefabriken Lindt & Sprü | Consumer Defensive | 15 | -15 | -12% |
Regime Monitor
The three breadth conditions that carried a measured forward edge in our backtest, tracked as episodes. Full detail at chartlas.com/regime.
| Marker | State on Oct 2, 2026 | Last episode | Past 12 months |
|---|---|---|---|
| Breadth washout (S&P, <20% above 200-DMA) | 41.6% — neutral zone | Apr 8, 2025 | 0 |
| Hindenburg Omen (global universe) | quiet | Jun 1, 2026 | 3 episodes |
| 90% down-volume day (S&P) | none this week | Dec 31, 2025 | 2 |
| 90% up-volume day (S&P) | none this week | May 27, 2025 | 0 |
How we read it: nothing on the board argues for either aggression or defense right now — the washout gauge sits at 42%, mid-zone. The washout line at 20% is the nearer boundary if the current move extends. 3 global Hindenburg episodes inside twelve months is above the long-run cadence of roughly two — the split-market condition (heavy new highs and new lows together) keeps recurring, and the month after an episode has averaged about three points below a typical month in our history. The most recent (Jun 1, 2026) is stale; a fresh one would move this from footnote to headline. No 90% volume days this week (last down-day episode: Dec 31, 2025).
Where the Signals Are — Industry Scan
The week's cumulative signal net per industry (Investable universe), scored against that industry's own year of weekly readings. Click any name to open it in the Explorer.
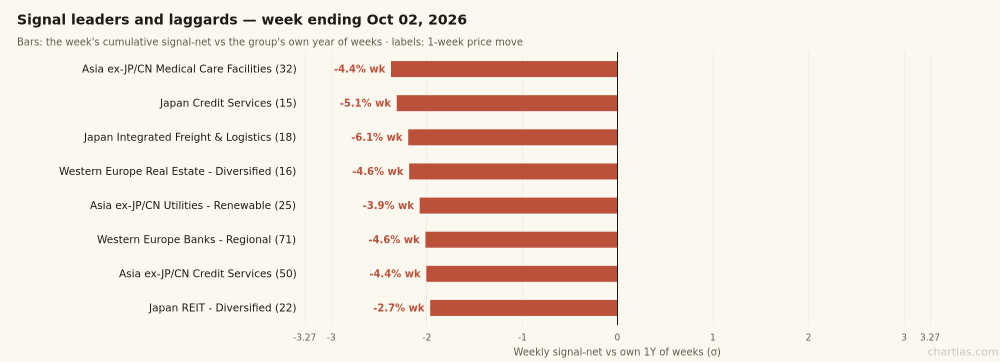
Bars: the week's cumulative signal-net vs the group's own year of weeks. Labels: the same group's 1-week price move.
Signal leaders: no industry cleared the ±1.8σ bar this week.
Signal laggards:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Asia ex-JP/CN Medical Care Facilities | -104 | -2.4σ | 32 | -4.4% |
| Japan Credit Services | -67 | -2.3σ | 15 | -5.1% |
| Japan Integrated Freight & Logistics | -74 | -2.2σ | 18 | -6.1% |
| Western Europe Real Estate - Diversified | -70 | -2.2σ | 16 | -4.6% |
| Asia ex-JP/CN Utilities - Renewable | -68 | -2.1σ | 25 | -3.9% |
| Western Europe Banks - Regional | -217 | -2.0σ | 71 | -4.6% |
| Asia ex-JP/CN Credit Services | -128 | -2.0σ | 50 | -4.4% |
| Japan REIT - Diversified | -126 | -2.0σ | 22 | -2.7% |
The read. The laggards are equally one theme — Asia ex-JP/CN — and there the composition inverts: of Western Europe Banks - Regional's 367 bearish fires this week, 243 were trend-family breakdowns. Downtrend intact — another week, more groups.
Rotation & Divergences
Structural flags from the CHRT tree this week.
3 divergence flags tripped this week (2 hidden-base, 1 thin-rally), but no cross-regional cluster — no sector set off the same flag in two or more regions, which is the coincidence we treat as signal.
Leadership changes worth noting (which industry drives its group's signal activity): - Western Europe Real Estate — Western Europe Real Estate took the lead from Western Europe REITs (10-01).
Sharpest single-day surprises: Latin America Department Stores printed a -22 net signal day on 10-02 (-3.1σ); Japan Integrated Freight & Logistics printed a -41 net signal day on 09-29 (-2.8σ) — worth a look if you own the space.
Geography Scan
The week's cumulative signal net per region vs that region's own year of weekly readings, alongside the week's price move.
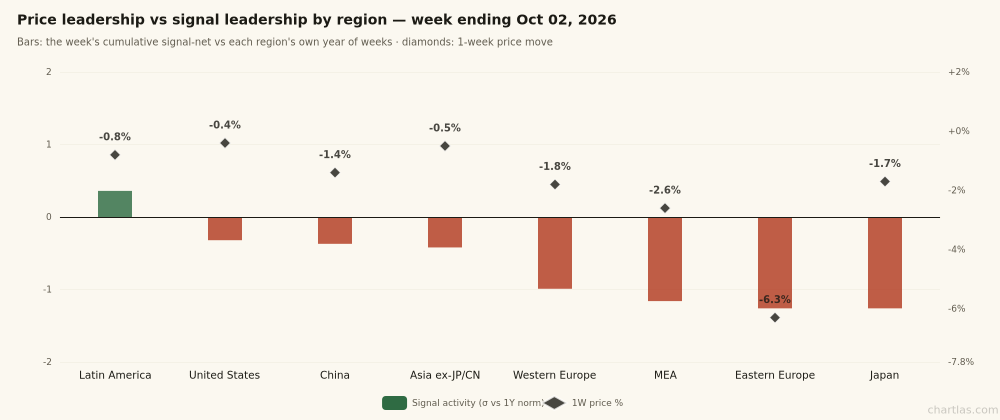
Bars: the week's cumulative signal-net vs each region's own year of weeks. Diamonds: 1-week price move.
| Region | Weekly net | σ (1Y wks) | 1W price |
|---|---|---|---|
| Latin America | +291 | +0.4σ | -0.8% |
| United States | -9 | -0.3σ | -0.4% |
| China | -3,811 | -0.4σ | -1.4% |
| Asia ex-JP/CN | -409 | -0.4σ | -0.5% |
| Western Europe | -1,357 | -1.0σ | -1.8% |
| Middle East & Africa | -694 | -1.2σ | -2.6% |
| Eastern Europe | -587 | -1.3σ | -6.3% |
| Japan | -2,459 | -1.3σ | -1.7% |
The read: Eastern Europe is red on both counts: -6.3% with a -1.3σ signal week. Japan is red on both counts: -1.7% with a -1.3σ signal week.
Momentum Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Advance / Decline | -14,272 | -8,354 | -5,918 | -0.9 | Weakening |
| New 20D High/Low | -13,331 | -5,076 | -8,255 | -1.7 | Weakening |
| MACD Breadth | -1,465 | +2,451 | -3,916 | -0.6 | Flipped bearish |
| RSI Extremes | +830 | +295 | +535 | +0.9 | Strengthening |
| Bollinger Band | +1,908 | +28 | +1,880 | +1.0 | Strengthening |
| Weekly Movers (±10%) | -1,986 | +3,768 | -5,754 | -0.8 | Flipped bearish |
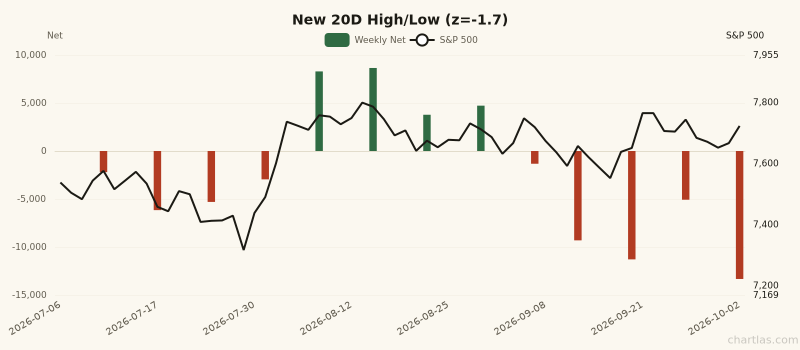
New 20D High/Low weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -1.7.
Trend Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| 52-Week High/Low | -3,825 | -1,494 | -2,331 | -1.7 | Weakening |
| Fresh 52W High/Low | -617 | -116 | -501 | -1.7 | Weakening |
| 200 DMA Breadth | -23,010 | -18,351 | -4,659 | -1.4 | Weakening |
| MA Cross (Golden/Death) | -76 | -103 | +27 | +0.0 | Improving |
| HH/HL Structure | -8 | +70 | -78 | -0.4 | Flipped bearish |
| Breakout / Breakdown | -259 | +191 | -450 | -1.8 | Flipped bearish |
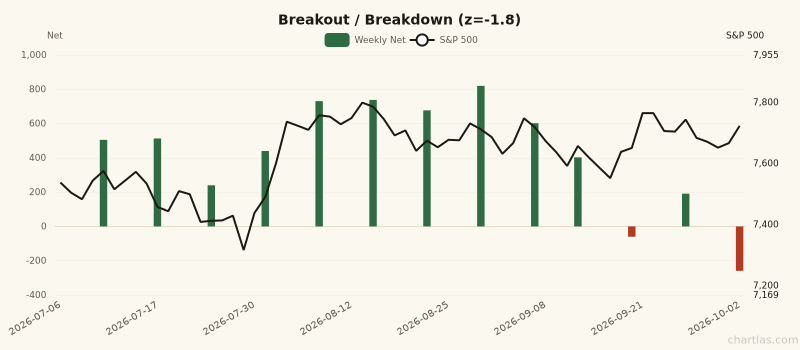
Breakout / Breakdown weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -1.8.
Pattern Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Double Top/Bottom | -419 | -181 | -238 | -1.2 | Weakening |
| Failed Pattern | -68 | -5 | -63 | -0.3 | Weakening |
Major ETF Signals
| Ticker | Name | Momentum | Trend | Pattern | Net | Z (1Y) |
|---|---|---|---|---|---|---|
| GLD | Gold | 4↑ 1↓ | — | — | +3 | +0.3 |
| EWJ | Japan | 1↑ | 3↑ 2↓ | — | +2 | +0.2 |
| USO | Oil (USO) | 2↑ | 1↑ 1↓ | — | +2 | +0.1 |
| IWM | Russell 2000 | 4↑ 2↓ | 2↓ | — | +0 | -0.5 |
| QQQ | NASDAQ 100 | 2↓ | 2↑ | — | +0 | -0.4 |
| VGK | FTSE Europe | — | — | — | +0 | — |
| EEM | Emerging Markets | 1↓ | 1↑ 1↓ | — | -1 | -0.7 |
| EFA | EAFE (Dev ex-US) | 4↑ 4↓ | 1↓ | — | -1 | -0.6 |
| IBIT | Bitcoin | 2↓ | 1↑ | — | -1 | -0.1 |
| DIA | Dow Jones | 3↑ 2↓ | 3↓ | — | -2 | -0.9 |
| SPY | S&P 500 | 2↓ | 1↑ 1↓ | — | -2 | -1.0 |
| HYG | High Yield Corp | 4↑ 5↓ | 3↓ | — | -4 | -1.1 |
| TLT | 20+ Year Treasury | 3↑ 3↓ | 4↓ | — | -4 | -1.1 |
ETF board quiet again — 6 weeks running inside 2σ.
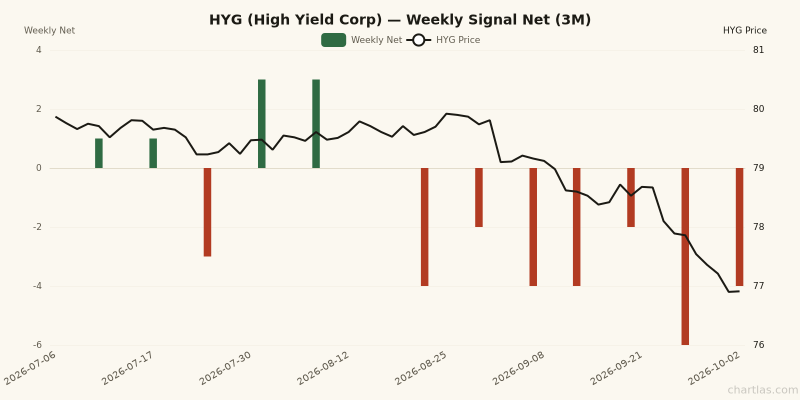
HYG weekly net signals (bars) with HYG price (blue line, right axis). 1Y z-score: -1.1.
Sector Breadth (Advance/Decline)
| Sector | Net | % Bullish | Z (1Y) |
|---|---|---|---|
| Utilities | -147 | 47.1% | -0.5 |
| Energy | -252 | 45.7% | -0.8 |
| Technology | -549 | 48.1% | -0.1 |
| Communication Services | -701 | 40.8% | -1.1 |
| Healthcare | -964 | 45.1% | -0.3 |
| Consumer Defensive | -1,124 | 41.0% | -1.3 |
| Real Estate | -1,304 | 38.6% | -1.5 |
| Basic Materials | -1,921 | 40.4% | -1.1 |
| Consumer Cyclical | -1,941 | 42.2% | -0.8 |
| Financial Services | -2,044 | 40.7% | -1.7 |
| Industrials | -2,511 | 43.7% | -0.7 |
No sector's advance/decline week stands out against its own year — rotation, not conviction.
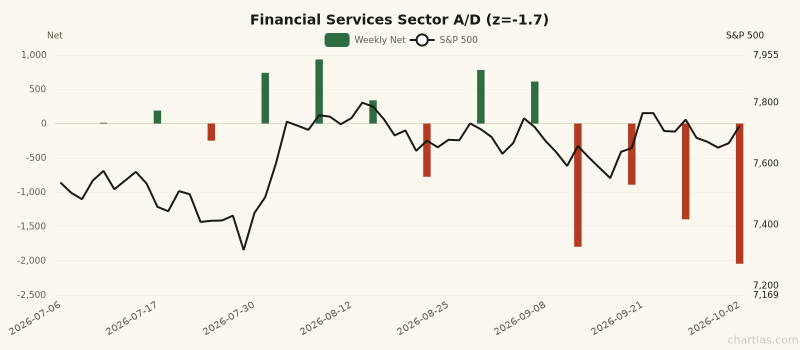
Financial Services sector weekly A/D net with S&P 500 price (right axis). 1Y z-score: -1.7.
What to Watch Next Week
- HH/HL Structure at -8 — the closest breadth index to a sign flip. The side it lands on next week is information.
Last Week We Said
From our report of Sep 25, 2026:
- 🟡 S&P 500: Rallied +1.2% to 7,743, but breadth is not fully confirming. Price is moving up while internals remain mixed.
- 🟢 MSCI World (ACWI): Gained +1.1%, tracking US markets. The rally is global.
- 🟡 The regime board is quiet. No washout (46% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Last week's report leaned bullish (1 green, 2 amber, 0 red). What happened: the S&P moved -0.3%. Mixed week, mixed call — no point claimed either way. The tally continues next week.
Generated by Chartlas — equity screening & signal alerts for discretionary investors. Forward-return references are averages from our 2015–2026 backtest on ~31,000 securities; they are tendencies, not predictions. Full methodology on the Regime and Breadth pages. Not investment advice.
Get this report in your inbox every Saturday
Free for all Chartlas users. Plus daily signal alerts, custom screens, PDF exports, and live breadth/regime dashboards.
Create free account →