Weekly Market Breadth Report — November 13, 2026
Generated automatically from Chartlas market data; methodology at /docs/methodology. Not investment advice.
Market Overview
S&P 500 rallied this week (+2.5%) to 7,562. MSCI World (ACWI) gained +2.4% to 156. Momentum is strong (6/6) while trend structure is weak (1/6). A vigorous bounce within a broken trend — modestly above-average forward returns historically, especially the following week. Best performer: Nikkei 225 (+6.5%). Weakest: Hang Seng (-3.4%).
| Metric | This Week | Last Week | 1Y Avg | Z (1Y) |
|---|---|---|---|---|
| Bullish Signal % | 57.7% | 50.1% | 51.6% | +0.7 |
| Bullish Signals | 98,969 | 114,426 | ||
| Bearish Signals | 72,420 | 114,108 |
Slightly more bullish than the 1-year weekly average (z=+0.7).
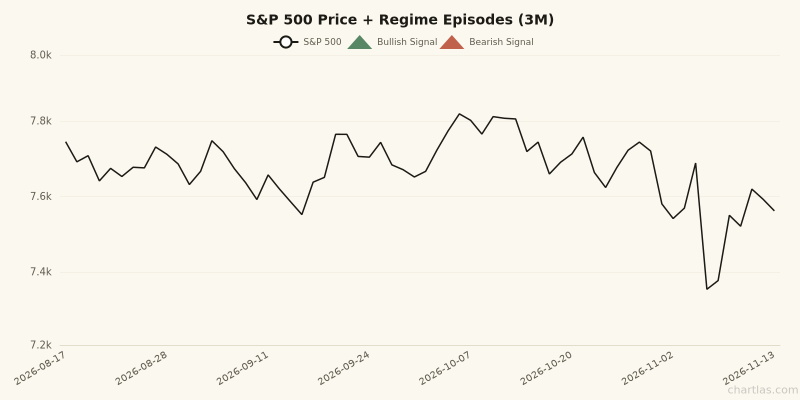
S&P 500 with regime episode markers — one marker per episode, matching the /regime monitor. Green = washouts / 90% up-volume days, red = global Hindenburg episodes / 90% down-volume days.
Key Takeaways
- 🟡 S&P 500: Rallied +2.5% to 7,562, but breadth is not fully confirming. Price is moving up while internals remain mixed.
- 🟢 MSCI World (ACWI): Gained +2.4%, tracking US markets. The rally is global.
- 🟢 MSCI World fired a bullish stochastic cross on Monday (chart, Nov 9, index at 4,846) — slow %K turned up through %D from the oversold zone. Since 2015, the five sessions after this cross have averaged +0.7% against +0.2% for a typical five-session stretch, finishing positive 68% of the time (n=103). A modest historical tilt, not a forecast.
- 🟢 The week's bullish theme is Japan. 5 of the top 8 industry surges are Japan groups with +3% to +12% price weeks.
- 🟡 The regime board is quiet. No washout (65% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Stocks with the Most Signals
Large-cap stocks ($10B+) with 5+ signals fired this week.
| Symbol | Name | Sector | Signals | Net | 1W % |
|---|---|---|---|---|---|
| 688585.SS | Swancor Advanced Materials Co. | Basic Materials | 18 | +8 | +18% |
| AC.MX | Arca Continental, S.A.B. de C. | Consumer Defensive | 17 | +11 | +4% |
| 2914.T | Japan Tobacco Inc. | Consumer Defensive | 17 | +3 | -5% |
| PNB.NS | Punjab National Bank | Financial Services | 17 | +13 | +13% |
| 3402.T | Toray Industries, Inc. | Consumer Cyclical | 16 | +10 | +17% |
| 5838.T | Rakuten Bank, Ltd. | Financial Services | 16 | -4 | -6% |
| RKLB | Rocket Lab Corporation | Industrials | 15 | +9 | +16% |
| FROG | JFrog Ltd. | Technology | 15 | +13 | +12% |
Regime Monitor
The three breadth conditions that carried a measured forward edge in our backtest, tracked as episodes. Full detail at chartlas.com/regime.
| Marker | State on Nov 13, 2026 | Last episode | Past 12 months |
|---|---|---|---|
| Breadth washout (S&P, <20% above 200-DMA) | 64.7% — neutral zone | Apr 8, 2025 | 0 |
| Hindenburg Omen (global universe) | quiet | Jun 1, 2026 | 3 episodes |
| 90% down-volume day (S&P) | none this week | Dec 31, 2025 | 1 |
| 90% up-volume day (S&P) | none this week | May 27, 2025 | 0 |
How we read it: nothing on the board argues for either aggression or defense right now — the washout gauge sits at 65%, mid-zone. The overbought line at 80% is the nearer boundary if the current move extends. 3 global Hindenburg episodes inside twelve months is above the long-run cadence of roughly two — the split-market condition (heavy new highs and new lows together) keeps recurring, and the month after an episode has averaged about three points below a typical month in our history. The most recent (Jun 1, 2026) is stale; a fresh one would move this from footnote to headline. No 90% volume days this week (last down-day episode: Dec 31, 2025).
Where the Signals Are — Industry Scan
The week's cumulative signal net per industry (Investable universe), scored against that industry's own year of weekly readings. Click any name to open it in the Explorer.
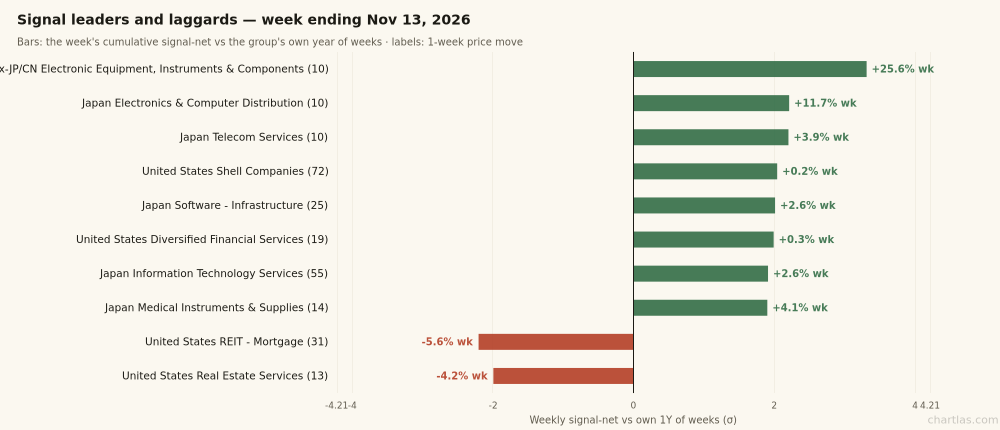
Bars: the week's cumulative signal-net vs the group's own year of weeks. Labels: the same group's 1-week price move.
Signal leaders:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Asia ex-JP/CN Electronic Equipment, Instruments & Components | +89 | +3.3σ | 10 | +25.6% |
| Japan Electronics & Computer Distribution | +61 | +2.2σ | 10 | +11.7% |
| Japan Telecom Services | +38 | +2.2σ | 10 | +3.9% |
| United States Shell Companies | +85 | +2.0σ | 72 | +0.2% |
| Japan Software - Infrastructure | +86 | +2.0σ | 25 | +2.6% |
| United States Diversified Financial Services | +35 | +2.0σ | 19 | +0.3% |
| Japan Information Technology Services | +155 | +1.9σ | 55 | +2.6% |
| Japan Medical Instruments & Supplies | +47 | +1.9σ | 14 | +4.1% |
Signal laggards:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| United States REIT - Mortgage | -164 | -2.2σ | 31 | -5.6% |
| United States Real Estate Services | -69 | -2.0σ | 13 | -4.2% |
The read. The leaders are one theme — Japan (electronics & computer distribution, telecom services, software - infrastructure, information technology services) — and their bullish fires are dominated by the trend family: United States Shell Companies logged 232 bullish signals this week, 210 of them trend-type (breakouts, structure, moving-average confirmations) against 22 oversold-type. That is a rally the engine is confirming, not bottom-fishing.
On the bear side the composition inverts: of United States REIT - Mortgage's 208 bearish fires this week, 202 were trend-family breakdowns. Downtrend intact — another week, more groups.
Rotation & Divergences
Structural flags from the CHRT tree this week.
7 divergence flags tripped this week (7 hidden-base), but no cross-regional cluster — no sector set off the same flag in two or more regions, which is the coincidence we treat as signal.
Leadership changes worth noting (which industry drives its group's signal activity): - Middle East & Africa Industrials — Middle East & Africa Conglomerates took the lead from Middle East & Africa Business Services (11-09). - United States IT Hardware — United States Electronic Components took the lead from United States Computer Hardware (11-09). - United States Industrials — United States Industrial Equipment took the lead from United States Aerospace & Defense (11-09).
Sharpest single-day surprises: Asia ex-JP/CN Airlines printed a +43 net signal day on 11-10 (+2.7σ); United States Shell Companies printed a +37 net signal day on 11-09 (+2.5σ) — worth a look if you own the space.
Geography Scan
The week's cumulative signal net per region vs that region's own year of weekly readings, alongside the week's price move.
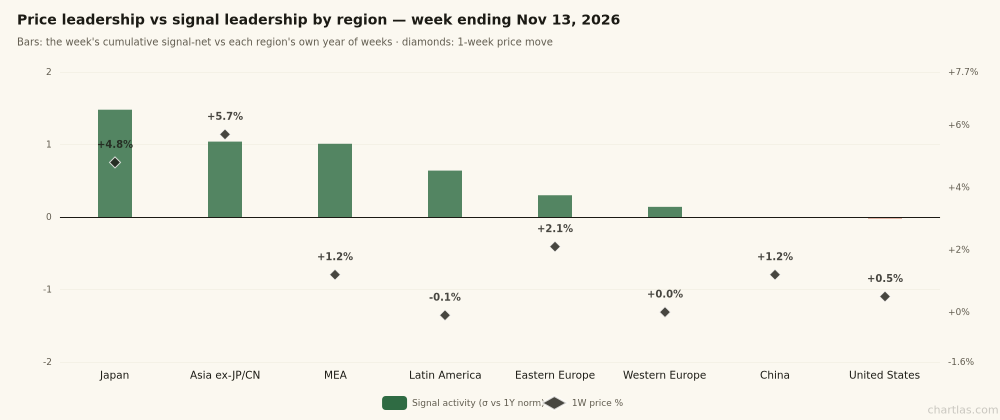
Bars: the week's cumulative signal-net vs each region's own year of weeks. Diamonds: 1-week price move.
| Region | Weekly net | σ (1Y wks) | 1W price |
|---|---|---|---|
| Japan | +5,221 | +1.5σ | +4.8% |
| Asia ex-JP/CN | +5,425 | +1.0σ | +5.7% |
| Middle East & Africa | +707 | +1.0σ | +1.2% |
| Latin America | +459 | +0.6σ | -0.1% |
| Eastern Europe | +400 | +0.3σ | +2.1% |
| Western Europe | +846 | +0.1σ | +0.0% |
| China | -373 | +0.0σ | +1.2% |
| United States | +1,013 | -0.0σ | +0.5% |
The read: Japan (+4.8%, +1.5σ) and Asia ex-JP/CN (+5.7%, +1.0σ) lead on both counts — price strength and participation agreeing at scale. Middle East & Africa: signal accumulation (+1.0σ) ahead of a flat tape (+1.2%) — participation building before price. United States is the weak tail of the board at -0.0σ.
Momentum Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Advance / Decline | +6,966 | -1,212 | +8,178 | +0.8 | Flipped bullish |
| New 20D High/Low | +3,100 | -8,452 | +11,552 | +0.6 | Flipped bullish |
| MACD Breadth | +3,314 | +2,452 | +862 | +1.3 | Strengthening |
| RSI Extremes | +2,317 | +2,970 | -653 | +1.6 | Deteriorating |
| Bollinger Band | +1,574 | +1,873 | -299 | +0.7 | Deteriorating |
| Weekly Movers (±10%) | +4,637 | -6,249 | +10,886 | +0.7 | Flipped bullish |
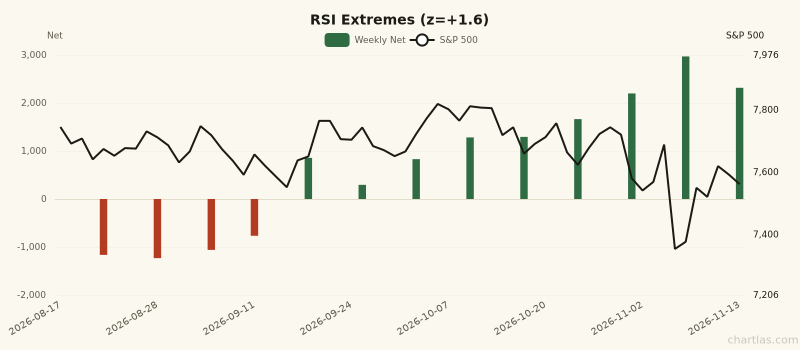
RSI Extremes weekly net (bars) with S&P 500 price (right axis). 1Y z-score: +1.6.
Trend Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| 52-Week High/Low | -754 | -6,376 | +5,622 | -0.4 | Improving |
| Fresh 52W High/Low | -99 | -1,276 | +1,177 | -0.3 | Improving |
| 200 DMA Breadth | -44,997 | -49,146 | +4,149 | -1.9 | Stable |
| MA Cross (Golden/Death) | -252 | -400 | +148 | -0.9 | Improving |
| HH/HL Structure | -182 | -382 | +200 | -0.7 | Improving |
| Breakout / Breakdown | +509 | +16 | +493 | +0.1 | Strengthening |
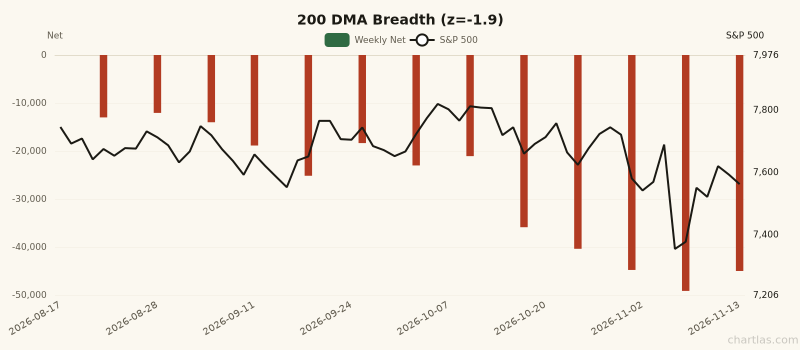
200 DMA Breadth weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -1.9.
Pattern Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Double Top/Bottom | -10 | -828 | +818 | +0.3 | Improving |
| Failed Pattern | +480 | +337 | +143 | +2.1 | Strengthening |
Major ETF Signals
| Ticker | Name | Momentum | Trend | Pattern | Net | Z (1Y) |
|---|---|---|---|---|---|---|
| EWJ | Japan | 5↑ | — | — | +5 | +1.2 |
| DIA | Dow Jones | 3↑ | 1↑ | — | +4 | +0.9 |
| USO | Oil (USO) | 4↑ 1↓ | 1↑ | — | +4 | +0.6 |
| QQQ | NASDAQ 100 | 3↑ | — | — | +3 | +0.2 |
| SPY | S&P 500 | 3↑ | 1↑ 1↓ | — | +3 | +0.2 |
| EEM | Emerging Markets | 2↑ | 1↑ 1↓ | — | +2 | +0.1 |
| EFA | EAFE (Dev ex-US) | 2↑ 2↓ | 1↑ | — | +1 | +0.0 |
| IBIT | Bitcoin | 3↑ 2↓ | 1↓ | — | +0 | +0.1 |
| VGK | FTSE Europe | — | — | — | +0 | — |
| HYG | High Yield Corp | — | 1↓ | — | -1 | -0.3 |
| IWM | Russell 2000 | 1↓ | 1↑ 1↓ | — | -1 | -0.7 |
| TLT | 20+ Year Treasury | 1↑ 2↓ | 2↓ | — | -3 | -0.8 |
| GLD | Gold | 3↓ | 3↓ | — | -6 | -1.6 |
Nothing on the ETF board is stretched beyond two standard deviations of its own one-year norm this week.
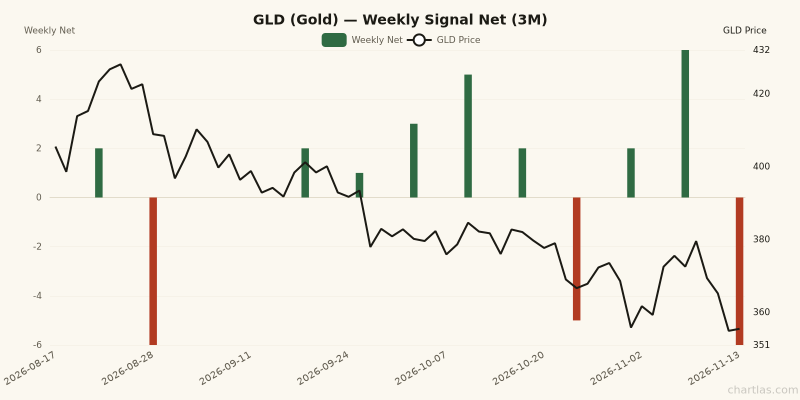
GLD weekly net signals (bars) with GLD price (blue line, right axis). 1Y z-score: -1.6.
Sector Breadth (Advance/Decline)
| Sector | Net | % Bullish | Z (1Y) |
|---|---|---|---|
| Technology | +2,286 | 56.2% | +1.1 |
| Industrials | +1,855 | 53.8% | +0.9 |
| Financial Services | +1,247 | 55.4% | +1.0 |
| Consumer Cyclical | +712 | 52.4% | +0.8 |
| Energy | +624 | 60.1% | +1.4 |
| Consumer Defensive | +460 | 53.2% | +1.0 |
| Communication Services | +378 | 54.3% | +1.2 |
| Real Estate | +217 | 51.7% | +0.6 |
| Utilities | +9 | 50.2% | +0.2 |
| Healthcare | -406 | 48.2% | +0.1 |
| Basic Materials | -484 | 48.0% | -0.1 |
Every sector inside its own one-year norm — rotation, no leadership.
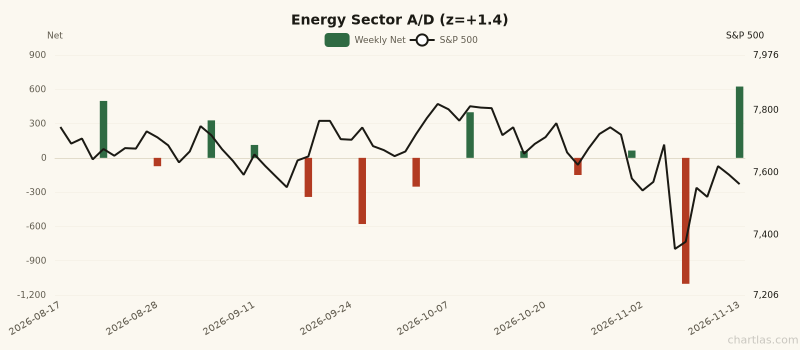
Energy sector weekly A/D net with S&P 500 price (right axis). 1Y z-score: +1.4.
What to Watch Next Week
- Does trend confirm? Momentum flipped (Advance / Decline); the rally graduates from bounce to trend only if 200 DMA Breadth or 52-Week High/Low turns positive.
- Double Top/Bottom at -10 sits a nudge from zero.
- The confirmed rallies (Asia ex-JP/CN and United States groups, +0% to +26% price weeks): whether trend-family confirmation persists, or the moves digest.
Last Week We Said
From our report of Nov 6, 2026:
- 🔴 S&P 500: Fell -2.7% to 7,377. Breadth confirms the weakness.
- 🔴 MSCI World (ACWI): Lost -2.4% — selling pressure is global.
- 🟢 MSCI World fired a bullish stochastic cross on Wednesday (chart, Nov 4, index at 4,922) — slow %K turned up through %D from the oversold zone. Since 2015, the five sessions after this cross have averaged
Last week's report leaned cautious (2 green, 0 amber, 4 red). What happened: the S&P rose +2.5%. Score it a miss. The cautious lean was wrong for the week. The tally continues next week.
Generated by Chartlas — equity screening & signal alerts for discretionary investors. Forward-return references are averages from our 2015–2026 backtest on ~31,000 securities; they are tendencies, not predictions. Full methodology on the Regime and Breadth pages. Not investment advice.
Get this report in your inbox every Saturday
Free for all Chartlas users. Plus daily signal alerts, custom screens, PDF exports, and live breadth/regime dashboards.
Create free account →