Weekly Market Breadth Report — October 16, 2026
Generated automatically from Chartlas market data; methodology at /docs/methodology. Not investment advice.
Market Overview
S&P 500 fell this week (-1.9%) to 7,659. MSCI World (ACWI) lost -2.0% to 158. Momentum is weak (2/6) while trend is in the mid-range (2/6). Short-term selling pressure within a mixed structural backdrop — below-average forward returns historically. Best performer: FTSE 100 (+3.1%). Weakest: Nikkei 225 (-5.4%).
| Metric | This Week | Last Week | 1Y Avg | Z (1Y) |
|---|---|---|---|---|
| Bullish Signal % | 45.6% | 52.6% | 52.1% | -0.8 |
| Bullish Signals | 89,906 | 89,954 | ||
| Bearish Signals | 107,435 | 80,937 |
Slightly more bearish than the 1-year weekly average (z=-0.8).
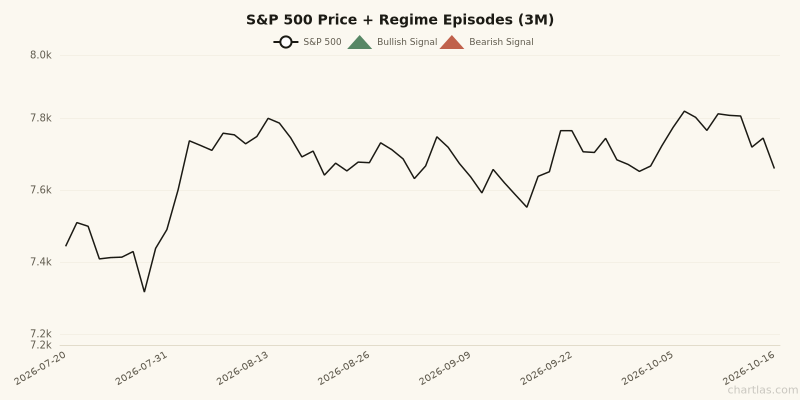
S&P 500 with regime episode markers — one marker per episode, matching the /regime monitor. Green = washouts / 90% up-volume days, red = global Hindenburg episodes / 90% down-volume days.
Key Takeaways
- 🔴 S&P 500: Fell -1.9% to 7,659. Breadth confirms the weakness.
- 🔴 MSCI World (ACWI): Lost -2.0% — selling pressure is global.
- 🔴 The weak side is one theme too — United States. 4 of the bottom 8 industry readings are United States groups.
- 🟡 The regime board is quiet. No washout (52% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Stocks with the Most Signals
Large-cap stocks ($10B+) with 5+ signals fired this week.
| Symbol | Name | Sector | Signals | Net | 1W % |
|---|---|---|---|---|---|
| 2603.TW | Evergreen Marine Corporation ( | Industrials | 23 | +15 | +14% |
| 005389.KS | Hyundai Motor Company | Consumer Cyclical | 18 | -8 | -3% |
| GME | GameStop Corp. | Consumer Cyclical | 18 | +6 | +1% |
| LPP.WA | LPP SA | Consumer Cyclical | 17 | +13 | +10% |
| IREN | IREN Limited | Financial Services | 17 | -9 | -23% |
| DOCU | DocuSign, Inc. | Technology | 17 | +5 | +5% |
| KOFUBL.MX | Coca-Cola FEMSA, S.A.B. de C.V | Consumer Defensive | 16 | +10 | +8% |
| GIVN.SW | Givaudan SA | Basic Materials | 16 | +14 | +14% |
Regime Monitor
The three breadth conditions that carried a measured forward edge in our backtest, tracked as episodes. Full detail at chartlas.com/regime.
| Marker | State on Oct 16, 2026 | Last episode | Past 12 months |
|---|---|---|---|
| Breadth washout (S&P, <20% above 200-DMA) | 51.9% — neutral zone | Apr 8, 2025 | 0 |
| Hindenburg Omen (global universe) | quiet | Jun 1, 2026 | 3 episodes |
| 90% down-volume day (S&P) | none this week | Dec 31, 2025 | 1 |
| 90% up-volume day (S&P) | none this week | May 27, 2025 | 0 |
How we read it: nothing on the board argues for either aggression or defense right now — the washout gauge sits at 52%, mid-zone. The overbought line at 80% is the nearer boundary if the current move extends. 3 global Hindenburg episodes inside twelve months is above the long-run cadence of roughly two — the split-market condition (heavy new highs and new lows together) keeps recurring, and the month after an episode has averaged about three points below a typical month in our history. The most recent (Jun 1, 2026) is stale; a fresh one would move this from footnote to headline. No 90% volume days this week (last down-day episode: Dec 31, 2025).
Where the Signals Are — Industry Scan
The week's cumulative signal net per industry (Investable universe), scored against that industry's own year of weekly readings. Click any name to open it in the Explorer.
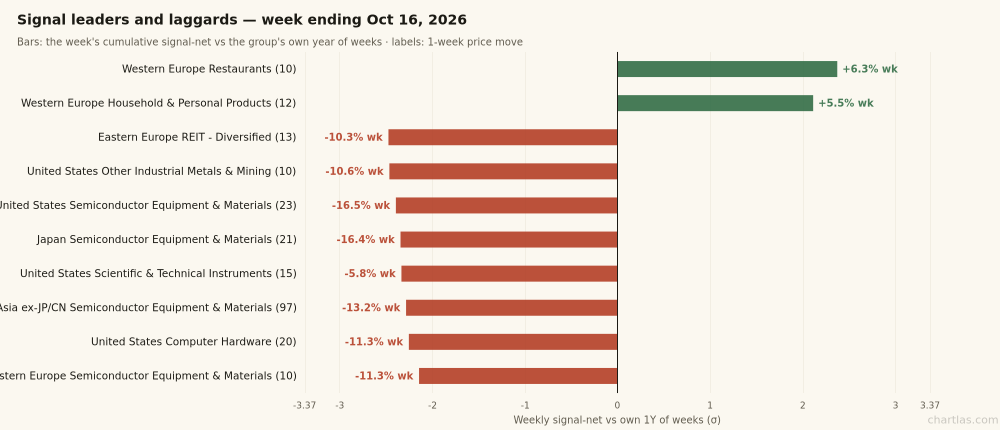
Bars: the week's cumulative signal-net vs the group's own year of weeks. Labels: the same group's 1-week price move.
Signal leaders:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Western Europe Restaurants | +56 | +2.4σ | 10 | +6.3% |
| Western Europe Household & Personal Products | +50 | +2.1σ | 12 | +5.5% |
Signal laggards:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| Eastern Europe REIT - Diversified | -69 | -2.5σ | 13 | -10.3% |
| United States Other Industrial Metals & Mining | -49 | -2.5σ | 10 | -10.6% |
| United States Semiconductor Equipment & Materials | -164 | -2.4σ | 23 | -16.5% |
| Japan Semiconductor Equipment & Materials | -126 | -2.3σ | 21 | -16.4% |
| United States Scientific & Technical Instruments | -51 | -2.3σ | 15 | -5.8% |
| Asia ex-JP/CN Semiconductor Equipment & Materials | -401 | -2.3σ | 97 | -13.2% |
| United States Computer Hardware | -101 | -2.2σ | 20 | -11.3% |
| Western Europe Semiconductor Equipment & Materials | -55 | -2.1σ | 10 | -11.3% |
The read. The strongest surge has trend-family confirmation: Western Europe Restaurants logged 67 bullish signals this week, 59 of them trend-type (breakouts, structure, moving-average confirmations) against 6 oversold-type. That is a rally the engine is confirming, not bottom-fishing.
The laggards are equally one theme — United States — and there the composition inverts: of Asia ex-JP/CN Semiconductor Equipment & Materials's 579 bearish fires this week, 422 were trend-family breakdowns. Downtrend intact — another week, more groups.
The oversold nuance — read this before buying the dip. Inside that net-bearish week, the final session alone produced 69 bullish fires in Asia ex-JP/CN Semiconductor Equipment & Materials, and 50 of them were mean-reversion signals — oversold readings, not trend signals. The sell-off has pushed an unusually broad share of the group to statistically stretched levels. Readings like that are dip signals inside an intact downtrend — they mark where bounce candidates live, not a trend reversal. The tell that would change our read is the weekly net flipping positive. Until then, oversold means "stretched," not "safe."
Rotation & Divergences
Structural flags from the CHRT tree this week.
5 divergence flags tripped this week (5 hidden-base), but no cross-regional cluster — no sector set off the same flag in two or more regions, which is the coincidence we treat as signal.
Sharpest single-day surprises: Japan Semiconductor Equipment & Materials printed a -71 net signal day on 10-15 (-3.1σ); Japan Semiconductors printed a -107 net signal day on 10-15 (-3.1σ) — worth a look if you own the space.
Geography Scan
The week's cumulative signal net per region vs that region's own year of weekly readings, alongside the week's price move.
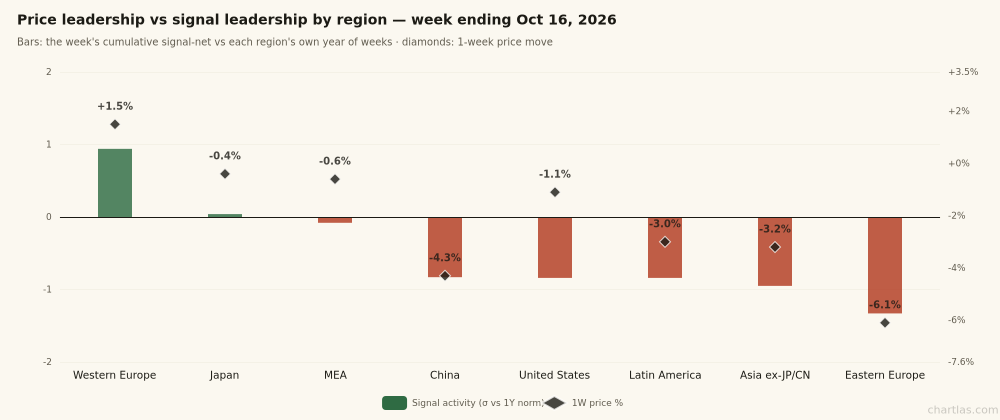
Bars: the week's cumulative signal-net vs each region's own year of weeks. Diamonds: 1-week price move.
| Region | Weekly net | σ (1Y wks) | 1W price |
|---|---|---|---|
| Western Europe | +2,422 | +0.9σ | +1.5% |
| Japan | +1,376 | +0.0σ | -0.4% |
| Middle East & Africa | +4 | -0.1σ | -0.6% |
| China | -8,785 | -0.8σ | -4.3% |
| United States | -1,912 | -0.8σ | -1.1% |
| Latin America | -362 | -0.8σ | -3.0% |
| Asia ex-JP/CN | -2,558 | -0.9σ | -3.2% |
| Eastern Europe | -654 | -1.3σ | -6.1% |
The read: Eastern Europe is red on both counts: -6.1% with a -1.3σ signal week.
Momentum Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Advance / Decline | -14,746 | -1,904 | -12,842 | -0.9 | Weakening |
| New 20D High/Low | -11,647 | -8,755 | -2,892 | -1.4 | Weakening |
| MACD Breadth | -591 | +1,188 | -1,779 | -0.2 | Flipped bearish |
| RSI Extremes | +1,294 | +1,283 | +11 | +1.2 | Stable |
| Bollinger Band | +2,983 | +2,146 | +837 | +1.4 | Strengthening |
| Weekly Movers (±10%) | -8,572 | +398 | -8,970 | -2.0 | Flipped bearish |
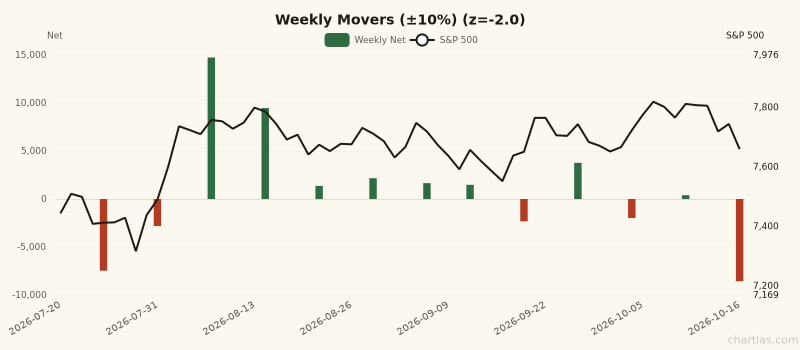
Weekly Movers (±10%) weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -2.0.
Trend Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| 52-Week High/Low | -4,288 | -2,797 | -1,491 | -1.7 | Weakening |
| Fresh 52W High/Low | -883 | -369 | -514 | -2.0 | Weakening |
| 200 DMA Breadth | -35,877 | -21,068 | -14,809 | -1.9 | Weakening |
| MA Cross (Golden/Death) | -73 | -74 | +1 | +0.2 | Stable |
| HH/HL Structure | +41 | +11 | +30 | -0.2 | Strengthening |
| Breakout / Breakdown | +211 | -62 | +273 | -0.7 | Flipped bullish |
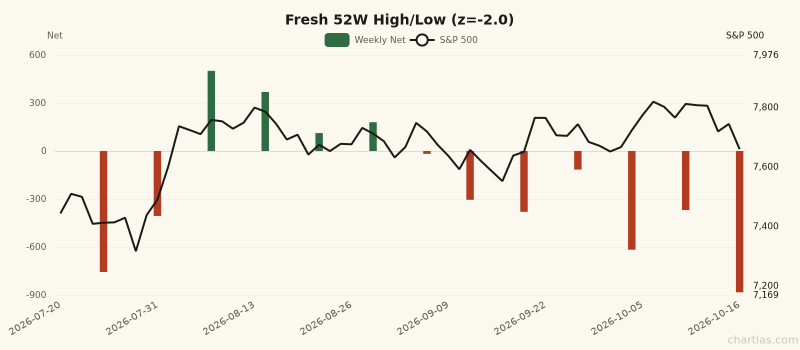
Fresh 52W High/Low weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -2.0.
Pattern Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Double Top/Bottom | -582 | -209 | -373 | -1.6 | Weakening |
| Failed Pattern | +17 | +21 | -4 | +0.0 | Deteriorating |
Major ETF Signals
| Ticker | Name | Momentum | Trend | Pattern | Net | Z (1Y) |
|---|---|---|---|---|---|---|
| USO | Oil (USO) | 3↑ | 2↑ | — | +5 | +0.8 |
| EFA | EAFE (Dev ex-US) | 3↑ | — | — | +3 | +0.5 |
| TLT | 20+ Year Treasury | 1↑ | 2↑ | — | +3 | +1.0 |
| GLD | Gold | 3↑ 1↓ | — | — | +2 | +0.2 |
| HYG | High Yield Corp | 2↑ | — | — | +2 | +0.7 |
| IBIT | Bitcoin | — | 2↑ 1↓ | — | +1 | +0.3 |
| VGK | FTSE Europe | — | — | — | +0 | — |
| IWM | Russell 2000 | 4↑ 3↓ | 2↓ | — | -1 | -0.7 |
| EWJ | Japan | — | 2↓ | — | -2 | -0.9 |
| DIA | Dow Jones | 3↓ | — | — | -3 | -1.2 |
| EEM | Emerging Markets | 2↓ | 1↓ | — | -3 | -1.2 |
| QQQ | NASDAQ 100 | 1↑ 2↓ | 2↓ | — | -3 | -1.0 |
| SPY | S&P 500 | 4↓ | 2↓ | — | -6 | -1.8 |
ETF board quiet again — 8 weeks running inside 2σ.
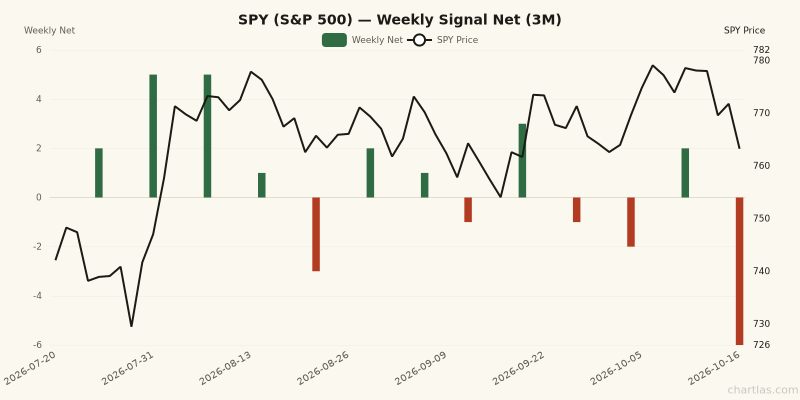
SPY weekly net signals (bars) with SPY price (blue line, right axis). 1Y z-score: -1.8.
Sector Breadth (Advance/Decline)
| Sector | Net | % Bullish | Z (1Y) |
|---|---|---|---|
| Energy | +59 | 51.0% | -0.0 |
| Communication Services | -10 | 49.9% | +0.3 |
| Consumer Defensive | -82 | 49.4% | +0.2 |
| Financial Services | -106 | 49.5% | -0.1 |
| Utilities | -183 | 46.7% | -0.6 |
| Real Estate | -215 | 48.1% | -0.0 |
| Consumer Cyclical | -789 | 47.1% | -0.2 |
| Basic Materials | -2,215 | 40.2% | -1.2 |
| Healthcare | -2,887 | 36.7% | -1.7 |
| Industrials | -3,170 | 43.0% | -0.9 |
| Technology | -4,257 | 37.2% | -1.5 |
Still no sector standing out — rotation without conviction, 3 weeks running.
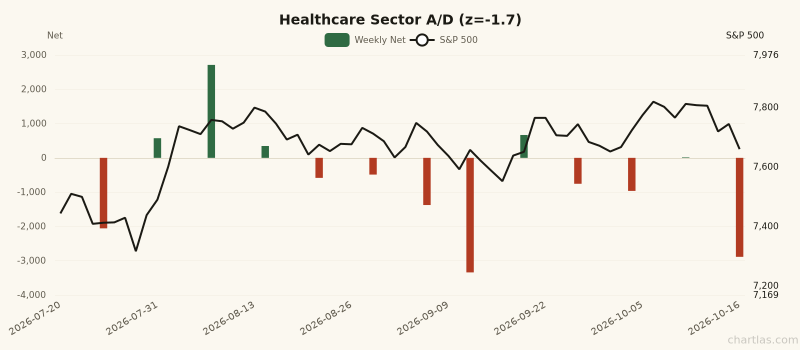
Healthcare sector weekly A/D net with S&P 500 price (right axis). 1Y z-score: -1.7.
What to Watch Next Week
- Asia ex-JP/CN Semiconductor Equipment & Materials's weekly net. The final-session oversold wave (50 mean-reversion bullish fires) landed inside a week of trend breakdowns. The tell is the weekly net flipping positive — until then it's a bounce setup inside a downtrend, not a turn.
- Failed Pattern at +17 — nearest to a sign flip. Watch which side it picks.
- The confirmed rallies (Western Europe groups, +6% to +6% price weeks): whether trend-family confirmation persists, or the moves digest.
Last Week We Said
From our report of Oct 9, 2026:
- 🟡 S&P 500: Rallied +1.2% to 7,812, but breadth is not fully confirming. Price is moving up while internals remain mixed.
- 🟢 Breadth: Momentum is mid-range (4/6) while trend structure is weak (1/6). The trend has been broken but momentum has not collapsed — the strongest setup in our backtest: +3.4% average over the following 4 weeks vs +1.1% baseline (p<0.01). Trend is starting to recover from its lows.
- 🟡 The regime board is quiet. No washout (47% above the 200-DMA), no capitulation days, last global Hindenburg episode Jun 1, 2026. Quiet is information too.
Last week's report leaned bullish (1 green, 2 amber, 0 red). What happened: the S&P fell -1.9%. Wrong side. The bullish lean was wrong for the week. The tally continues next week.
Generated by Chartlas — equity screening & signal alerts for discretionary investors. Forward-return references are averages from our 2015–2026 backtest on ~31,000 securities; they are tendencies, not predictions. Full methodology on the Regime and Breadth pages. Not investment advice.
Get this report in your inbox every Saturday
Free for all Chartlas users. Plus daily signal alerts, custom screens, PDF exports, and live breadth/regime dashboards.
Create free account →