Weekly Market Breadth Report — November 06, 2026
Generated automatically from Chartlas market data; methodology at /docs/methodology. Not investment advice.
Market Overview
S&P 500 fell this week (-2.7%) to 7,377. MSCI World (ACWI) lost -2.4% to 152. Momentum is mid-range (3/6) while trend structure is weak (1/6). The trend has been broken but momentum has not collapsed — the strongest setup in our backtest: +3.4% average over the following 4 weeks vs +1.1% baseline. Best performer: Hang Seng (+5.1%). Weakest: Nikkei 225 (-9.3%).
| Metric | This Week | Last Week | 1Y Avg | Z (1Y) |
|---|---|---|---|---|
| Bullish Signal % | 50.1% | 47.7% | 52.0% | -0.2 |
| Bullish Signals | 114,459 | 95,178 | ||
| Bearish Signals | 114,079 | 104,415 |
Signal balance is near its 1-year norm — nothing unusual this week.
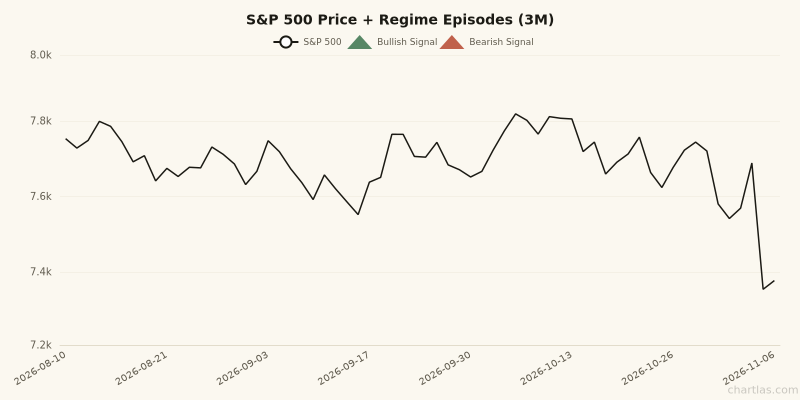
S&P 500 with regime episode markers — one marker per episode, matching the /regime monitor. Green = washouts / 90% up-volume days, red = global Hindenburg episodes / 90% down-volume days.
Key Takeaways
- 🔴 S&P 500: Fell -2.7% to 7,377. Breadth confirms the weakness.
- 🔴 MSCI World (ACWI): Lost -2.4% — selling pressure is global.
- 🟢 MSCI World fired a bullish stochastic cross on Wednesday (chart, Nov 4, index at 4,922) — slow %K turned up through %D from the oversold zone. Since 2015, the five sessions after this cross have averaged +0.7% against +0.2% for a typical five-session stretch, finishing positive 68% of the time (n=103). A modest historical tilt, not a forecast.
- 🟢 The week's bullish theme is China. 7 of the top 8 industry surges are China groups with +4% to +19% price weeks.
- 🔴 The weak side is one theme too — United States. 3 of the bottom 8 industry readings are United States groups.
- 🔴 USO is the outlier on the ETF board — net -9 signals, -2.1σ vs its one-year norm. Stretched readings more often mean-revert than continue, but the pressure has been persistent.
Stocks with the Most Signals
Large-cap stocks ($10B+) with 5+ signals fired this week.
| Symbol | Name | Sector | Signals | Net | 1W % |
|---|---|---|---|---|---|
| FIS | Fidelity National Information | Technology | 20 | -16 | -26% |
| 300274.SZ | Sungrow Power Supply Co., Ltd. | Industrials | 18 | +14 | +26% |
| CCO.TO | Cameco Corporation | Energy | 18 | -8 | -6% |
| W | Wayfair Inc. | Consumer Cyclical | 18 | -4 | -4% |
| ZTS | Zoetis Inc. | Healthcare | 18 | +2 | -0% |
| AMD | Advanced Micro Devices, Inc. | Technology | 18 | -2 | -11% |
| FROG | JFrog Ltd. | Technology | 18 | -4 | +7% |
| DLTR | Dollar Tree, Inc. | Consumer Defensive | 18 | +0 | -2% |
Regime Monitor
The three breadth conditions that carried a measured forward edge in our backtest, tracked as episodes. Full detail at chartlas.com/regime.
| Marker | State on Nov 6, 2026 | Last episode | Past 12 months |
|---|---|---|---|
| Breadth washout (S&P, <20% above 200-DMA) | 57.1% — neutral zone | Apr 8, 2025 | 0 |
| Hindenburg Omen (global universe) | quiet | Jun 1, 2026 | 3 episodes |
| 90% down-volume day (S&P) | none this week | Dec 31, 2025 | 1 |
| 90% up-volume day (S&P) | none this week | May 27, 2025 | 0 |
How we read it: nothing on the board argues for either aggression or defense right now — the washout gauge sits at 57%, mid-zone. The overbought line at 80% is the nearer boundary if the current move extends. 3 global Hindenburg episodes inside twelve months is above the long-run cadence of roughly two — the split-market condition (heavy new highs and new lows together) keeps recurring, and the month after an episode has averaged about three points below a typical month in our history. The most recent (Jun 1, 2026) is stale; a fresh one would move this from footnote to headline. No 90% volume days this week (last down-day episode: Dec 31, 2025).
Where the Signals Are — Industry Scan
The week's cumulative signal net per industry (Investable universe), scored against that industry's own year of weekly readings. Click any name to open it in the Explorer.
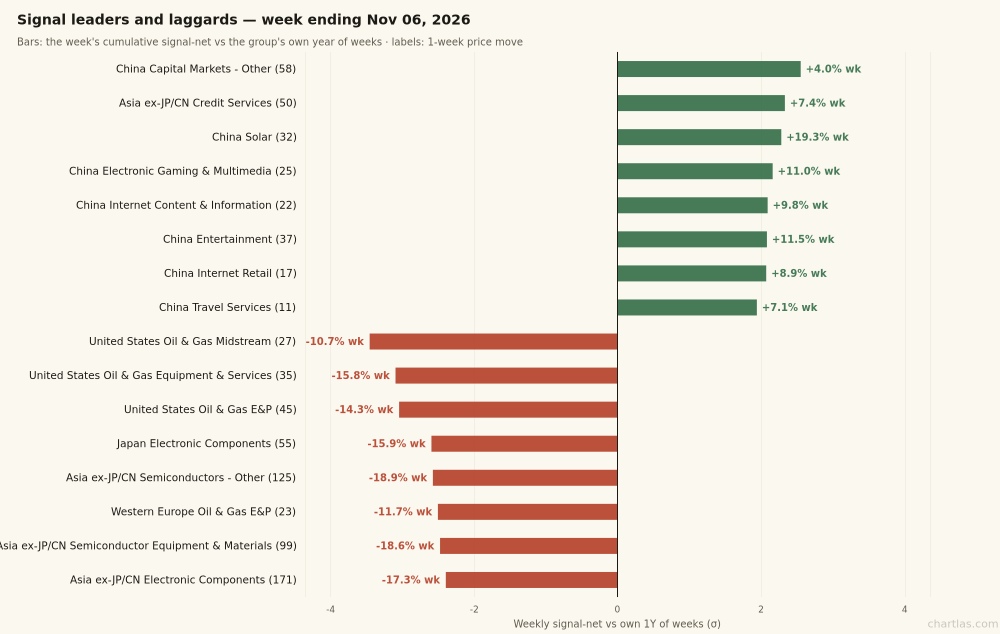
Bars: the week's cumulative signal-net vs the group's own year of weeks. Labels: the same group's 1-week price move.
Signal leaders:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| China Capital Markets - Other | +265 | +2.5σ | 58 | +4.0% |
| Asia ex-JP/CN Credit Services | +191 | +2.3σ | 50 | +7.4% |
| China Solar | +203 | +2.3σ | 32 | +19.3% |
| China Electronic Gaming & Multimedia | +123 | +2.2σ | 25 | +11.0% |
| China Internet Content & Information | +114 | +2.1σ | 22 | +9.8% |
| China Entertainment | +162 | +2.1σ | 37 | +11.5% |
| China Internet Retail | +73 | +2.1σ | 17 | +8.9% |
| China Travel Services | +46 | +1.9σ | 11 | +7.1% |
Signal laggards:
| Industry | Weekly net | σ (1Y wks) | Members | 1W price |
|---|---|---|---|---|
| United States Oil & Gas Midstream | -210 | -3.5σ | 27 | -10.7% |
| United States Oil & Gas Equipment & Services | -234 | -3.1σ | 35 | -15.8% |
| United States Oil & Gas E&P | -378 | -3.0σ | 45 | -14.3% |
| Japan Electronic Components | -302 | -2.6σ | 55 | -15.9% |
| Asia ex-JP/CN Semiconductors - Other | -692 | -2.6σ | 125 | -18.9% |
| Western Europe Oil & Gas E&P | -131 | -2.5σ | 23 | -11.7% |
| Asia ex-JP/CN Semiconductor Equipment & Materials | -497 | -2.5σ | 99 | -18.6% |
| Asia ex-JP/CN Electronic Components | -812 | -2.4σ | 171 | -17.3% |
The read. The leaders are one theme — China (capital markets - other, solar, electronic gaming & multimedia, internet content & information) — and their bullish fires are dominated by the trend family: China Solar logged 285 bullish signals this week, 206 of them trend-type (breakouts, structure, moving-average confirmations) against 74 oversold-type. That is a rally the engine is confirming, not bottom-fishing.
The laggards are equally one theme — United States — and there the composition inverts: of Asia ex-JP/CN Electronic Components's 1,247 bearish fires this week, 1,202 were trend-family breakdowns. Downtrend intact — another week, more groups.
The oversold nuance — read this before buying the dip. Inside that net-bearish week, the final session alone produced 84 bullish fires in Asia ex-JP/CN Electronic Components, and 80 of them were mean-reversion signals — oversold readings, not trend signals (1 other group in the laggard list printed the same pattern). The sell-off has pushed an unusually broad share of the group to statistically stretched levels. Readings like that are dip signals inside an intact downtrend — they mark where bounce candidates live, not a trend reversal. The tell that would change our read is the weekly net flipping positive. Until then, oversold means "stretched," not "safe."
Rotation & Divergences
Structural flags from the CHRT tree this week.
5 divergence flags tripped this week (5 hidden-base), but no cross-regional cluster — no sector set off the same flag in two or more regions, which is the coincidence we treat as signal.
Leadership changes worth noting (which industry drives its group's signal activity): - Japan Consumer Cyclical — Japan Auto took the lead from Japan Travel & Leisure (11-05). - Japan Internet & Media — Japan Internet Content & Information took the lead from Japan Electronic Gaming & Multimedia (11-05).
Sharpest single-day surprises: United States Drug Manufacturers - Specialty & Generic printed a -76 net signal day on 11-05 (-3.8σ); Japan Auto Manufacturers printed a +40 net signal day on 11-05 (+3.8σ) — worth a look if you own the space.
Geography Scan
The week's cumulative signal net per region vs that region's own year of weekly readings, alongside the week's price move.
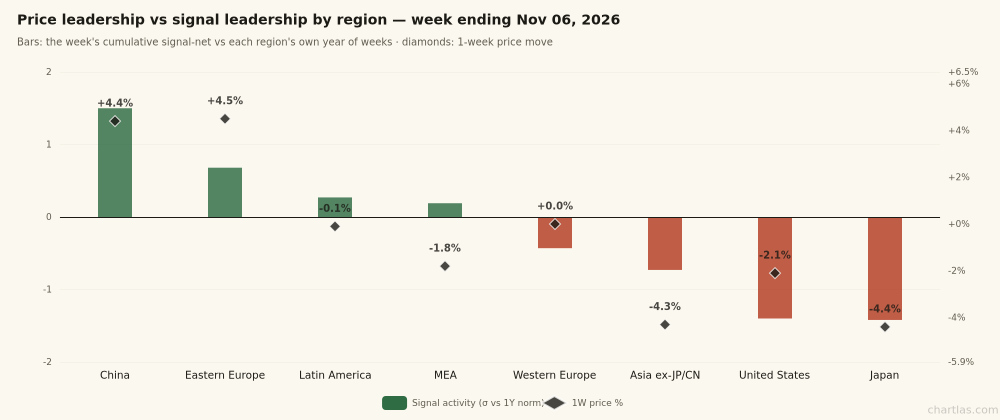
Bars: the week's cumulative signal-net vs each region's own year of weeks. Diamonds: 1-week price move.
| Region | Weekly net | σ (1Y wks) | 1W price |
|---|---|---|---|
| China | +14,985 | +1.5σ | +4.4% |
| Eastern Europe | +657 | +0.7σ | +4.5% |
| Latin America | +256 | +0.3σ | -0.1% |
| Middle East & Africa | +162 | +0.2σ | -1.8% |
| Western Europe | -270 | -0.4σ | +0.0% |
| Asia ex-JP/CN | -1,949 | -0.7σ | -4.3% |
| United States | -3,780 | -1.4σ | -2.1% |
| Japan | -2,860 | -1.4σ | -4.4% |
The read: China leads on both counts: +4.4% on the week with a +14,985 cumulative signal net (+1.5σ vs its own year) — the only region where price strength and participation agree at scale. United States is red on both counts: -2.1% with a -1.4σ signal week. Japan is red on both counts: -4.4% with a -1.4σ signal week.
Momentum Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Advance / Decline | -1,212 | -13,857 | +12,645 | +0.2 | Improving |
| New 20D High/Low | -8,452 | -10,397 | +1,945 | -0.8 | Improving |
| MACD Breadth | +2,452 | +595 | +1,857 | +1.0 | Strengthening |
| RSI Extremes | +2,970 | +2,199 | +771 | +2.2 | Strengthening |
| Bollinger Band | +1,873 | +2,384 | -511 | +0.9 | Deteriorating |
| Weekly Movers (±10%) | -6,249 | -5,246 | -1,003 | -1.4 | Weakening |
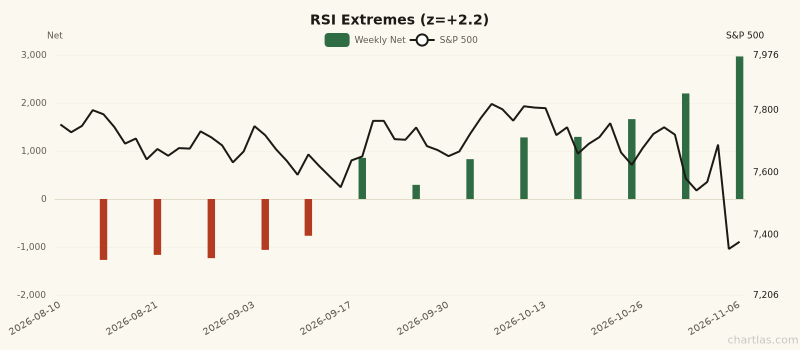
RSI Extremes weekly net (bars) with S&P 500 price (right axis). 1Y z-score: +2.2.
Trend Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| 52-Week High/Low | -6,376 | -5,115 | -1,261 | -2.0 | Weakening |
| Fresh 52W High/Low | -1,276 | -932 | -344 | -2.2 | Weakening |
| 200 DMA Breadth | -49,146 | -44,782 | -4,364 | -2.1 | Stable |
| MA Cross (Golden/Death) | -400 | -306 | -94 | -2.1 | Weakening |
| HH/HL Structure | -382 | -100 | -282 | -1.2 | Weakening |
| Breakout / Breakdown | +16 | +91 | -75 | -1.0 | Deteriorating |
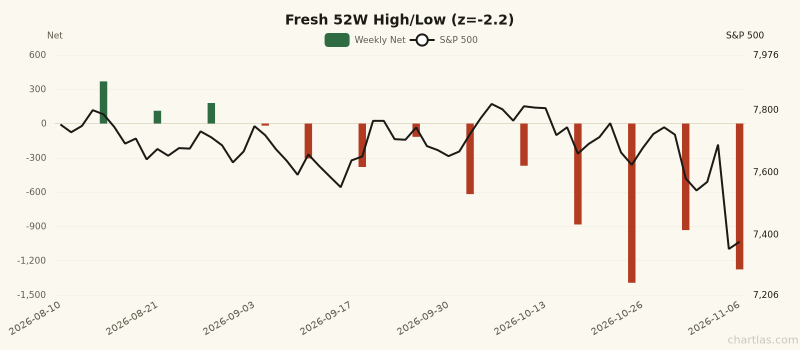
Fresh 52W High/Low weekly net (bars) with S&P 500 price (right axis). 1Y z-score: -2.2.
Pattern Breadth
| Index | This Week | Last Week | Change | Z (1Y) | Trend |
|---|---|---|---|---|---|
| Double Top/Bottom | -828 | -677 | -151 | -2.1 | Weakening |
| Failed Pattern | +337 | +139 | +198 | +1.5 | Strengthening |
Major ETF Signals
| Ticker | Name | Momentum | Trend | Pattern | Net | Z (1Y) |
|---|---|---|---|---|---|---|
| USO | Oil (USO) | 8↓ | 1↓ | — | -9 | -2.1 |
| GLD | Gold | 5↑ | 1↑ | — | +6 | +1.1 |
| EEM | Emerging Markets | 7↑ 2↓ | — | — | +5 | +0.9 |
| IBIT | Bitcoin | 5↑ 1↓ | — | — | +4 | +0.9 |
| SPY | S&P 500 | 4↑ 2↓ | 1↑ 2↓ | — | +1 | -0.3 |
| TLT | 20+ Year Treasury | 2↑ 2↓ | 1↑ | — | +1 | +0.4 |
| EWJ | Japan | 3↑ 2↓ | 1↓ | — | +0 | -0.3 |
| HYG | High Yield Corp | 1↑ | 1↑ 2↓ | — | +0 | +0.0 |
| VGK | FTSE Europe | — | — | — | +0 | — |
| QQQ | NASDAQ 100 | 4↑ 3↓ | 2↓ | — | -1 | -0.6 |
| DIA | Dow Jones | 3↑ 6↓ | 2↑ 2↓ | — | -3 | -1.2 |
| EFA | EAFE (Dev ex-US) | 1↑ 3↓ | 1↑ 2↓ | — | -3 | -1.2 |
| IWM | Russell 2000 | 1↑ 3↓ | 1↓ | — | -3 | -1.1 |
The one reading that stands out: USO (Oil (USO)) at a net -9 signal count, 2.1 standard deviations below its one-year norm — the most stretched reading on the board. Readings this stretched have more often marked exhaustion than acceleration, but we'd want to see the first bullish trend-family signal before calling it.
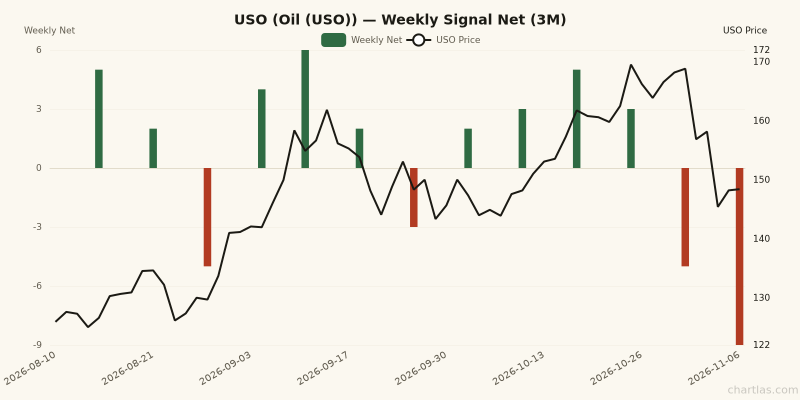
USO weekly net signals (bars) with USO price (blue line, right axis). 1Y z-score: -2.1.
Sector Breadth (Advance/Decline)
| Sector | Net | % Bullish | Z (1Y) |
|---|---|---|---|
| Consumer Cyclical | +780 | 52.7% | +0.8 |
| Basic Materials | +756 | 53.2% | +0.7 |
| Consumer Defensive | +488 | 53.4% | +1.1 |
| Utilities | +324 | 55.6% | +1.4 |
| Financial Services | +295 | 51.3% | +0.2 |
| Real Estate | +282 | 52.3% | +0.7 |
| Communication Services | +225 | 52.7% | +0.9 |
| Healthcare | +199 | 50.9% | +0.5 |
| Industrials | -217 | 49.5% | +0.2 |
| Energy | -1,102 | 32.5% | -2.8 |
| Technology | -2,788 | 42.2% | -0.9 |
On the other side, Energy is running -2.8σ below its one-year A/D norm.
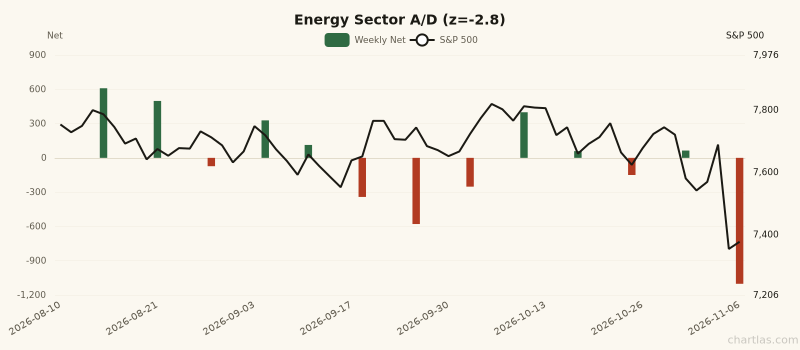
Energy sector weekly A/D net with S&P 500 price (right axis). 1Y z-score: -2.8.
What to Watch Next Week
- Asia ex-JP/CN Semiconductors - Other's weekly net. The final-session oversold wave (64 mean-reversion bullish fires) landed inside a week of trend breakdowns. The tell is the weekly net flipping positive — until then it's a bounce setup inside a downtrend, not a turn.
- Breakout / Breakdown at +16 — still hugging zero, second week.
- USO — the first bullish trend-family signal would mark the turn we're watching for.
- The confirmed rallies (Asia ex-JP/CN and China groups, +7% to +19% price weeks): whether trend-family confirmation persists, or the moves digest.
Last Week We Said
From our report of Oct 30, 2026:
- 🟡 S&P 500: Flat this week at 7,580 (-0.6%).
- 🟢 Breadth: Momentum is mid-range (3/6) while trend structure is weak (1/6). The trend has been broken but momentum has not collapsed — the strongest setup in our backtest: +3.4% average over the following 4 weeks vs +1.1% baseline (p<0.01). Trend is starting to recover from its lows.
- 🟢 MSCI World fired a bullish stochastic cross on Monday (chart, Oct 26, index at 4,901) — slow %K turned up through %D from the oversold zone. Since 2015, the five sessions after this cross have averaged +
Last week's report leaned bullish (2 green, 2 amber, 0 red). What happened: the S&P fell -2.7%. Wrong side. The bullish lean was wrong for the week. The tally continues next week.
Generated by Chartlas — equity screening & signal alerts for discretionary investors. Forward-return references are averages from our 2015–2026 backtest on ~31,000 securities; they are tendencies, not predictions. Full methodology on the Regime and Breadth pages. Not investment advice.
Get this report in your inbox every Saturday
Free for all Chartlas users. Plus daily signal alerts, custom screens, PDF exports, and live breadth/regime dashboards.
Create free account →